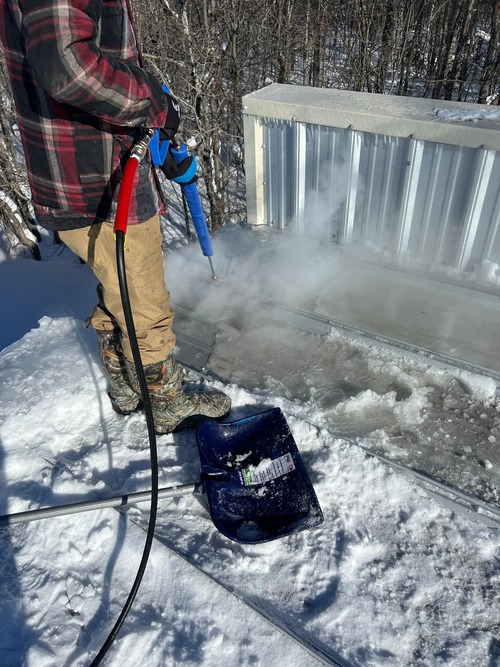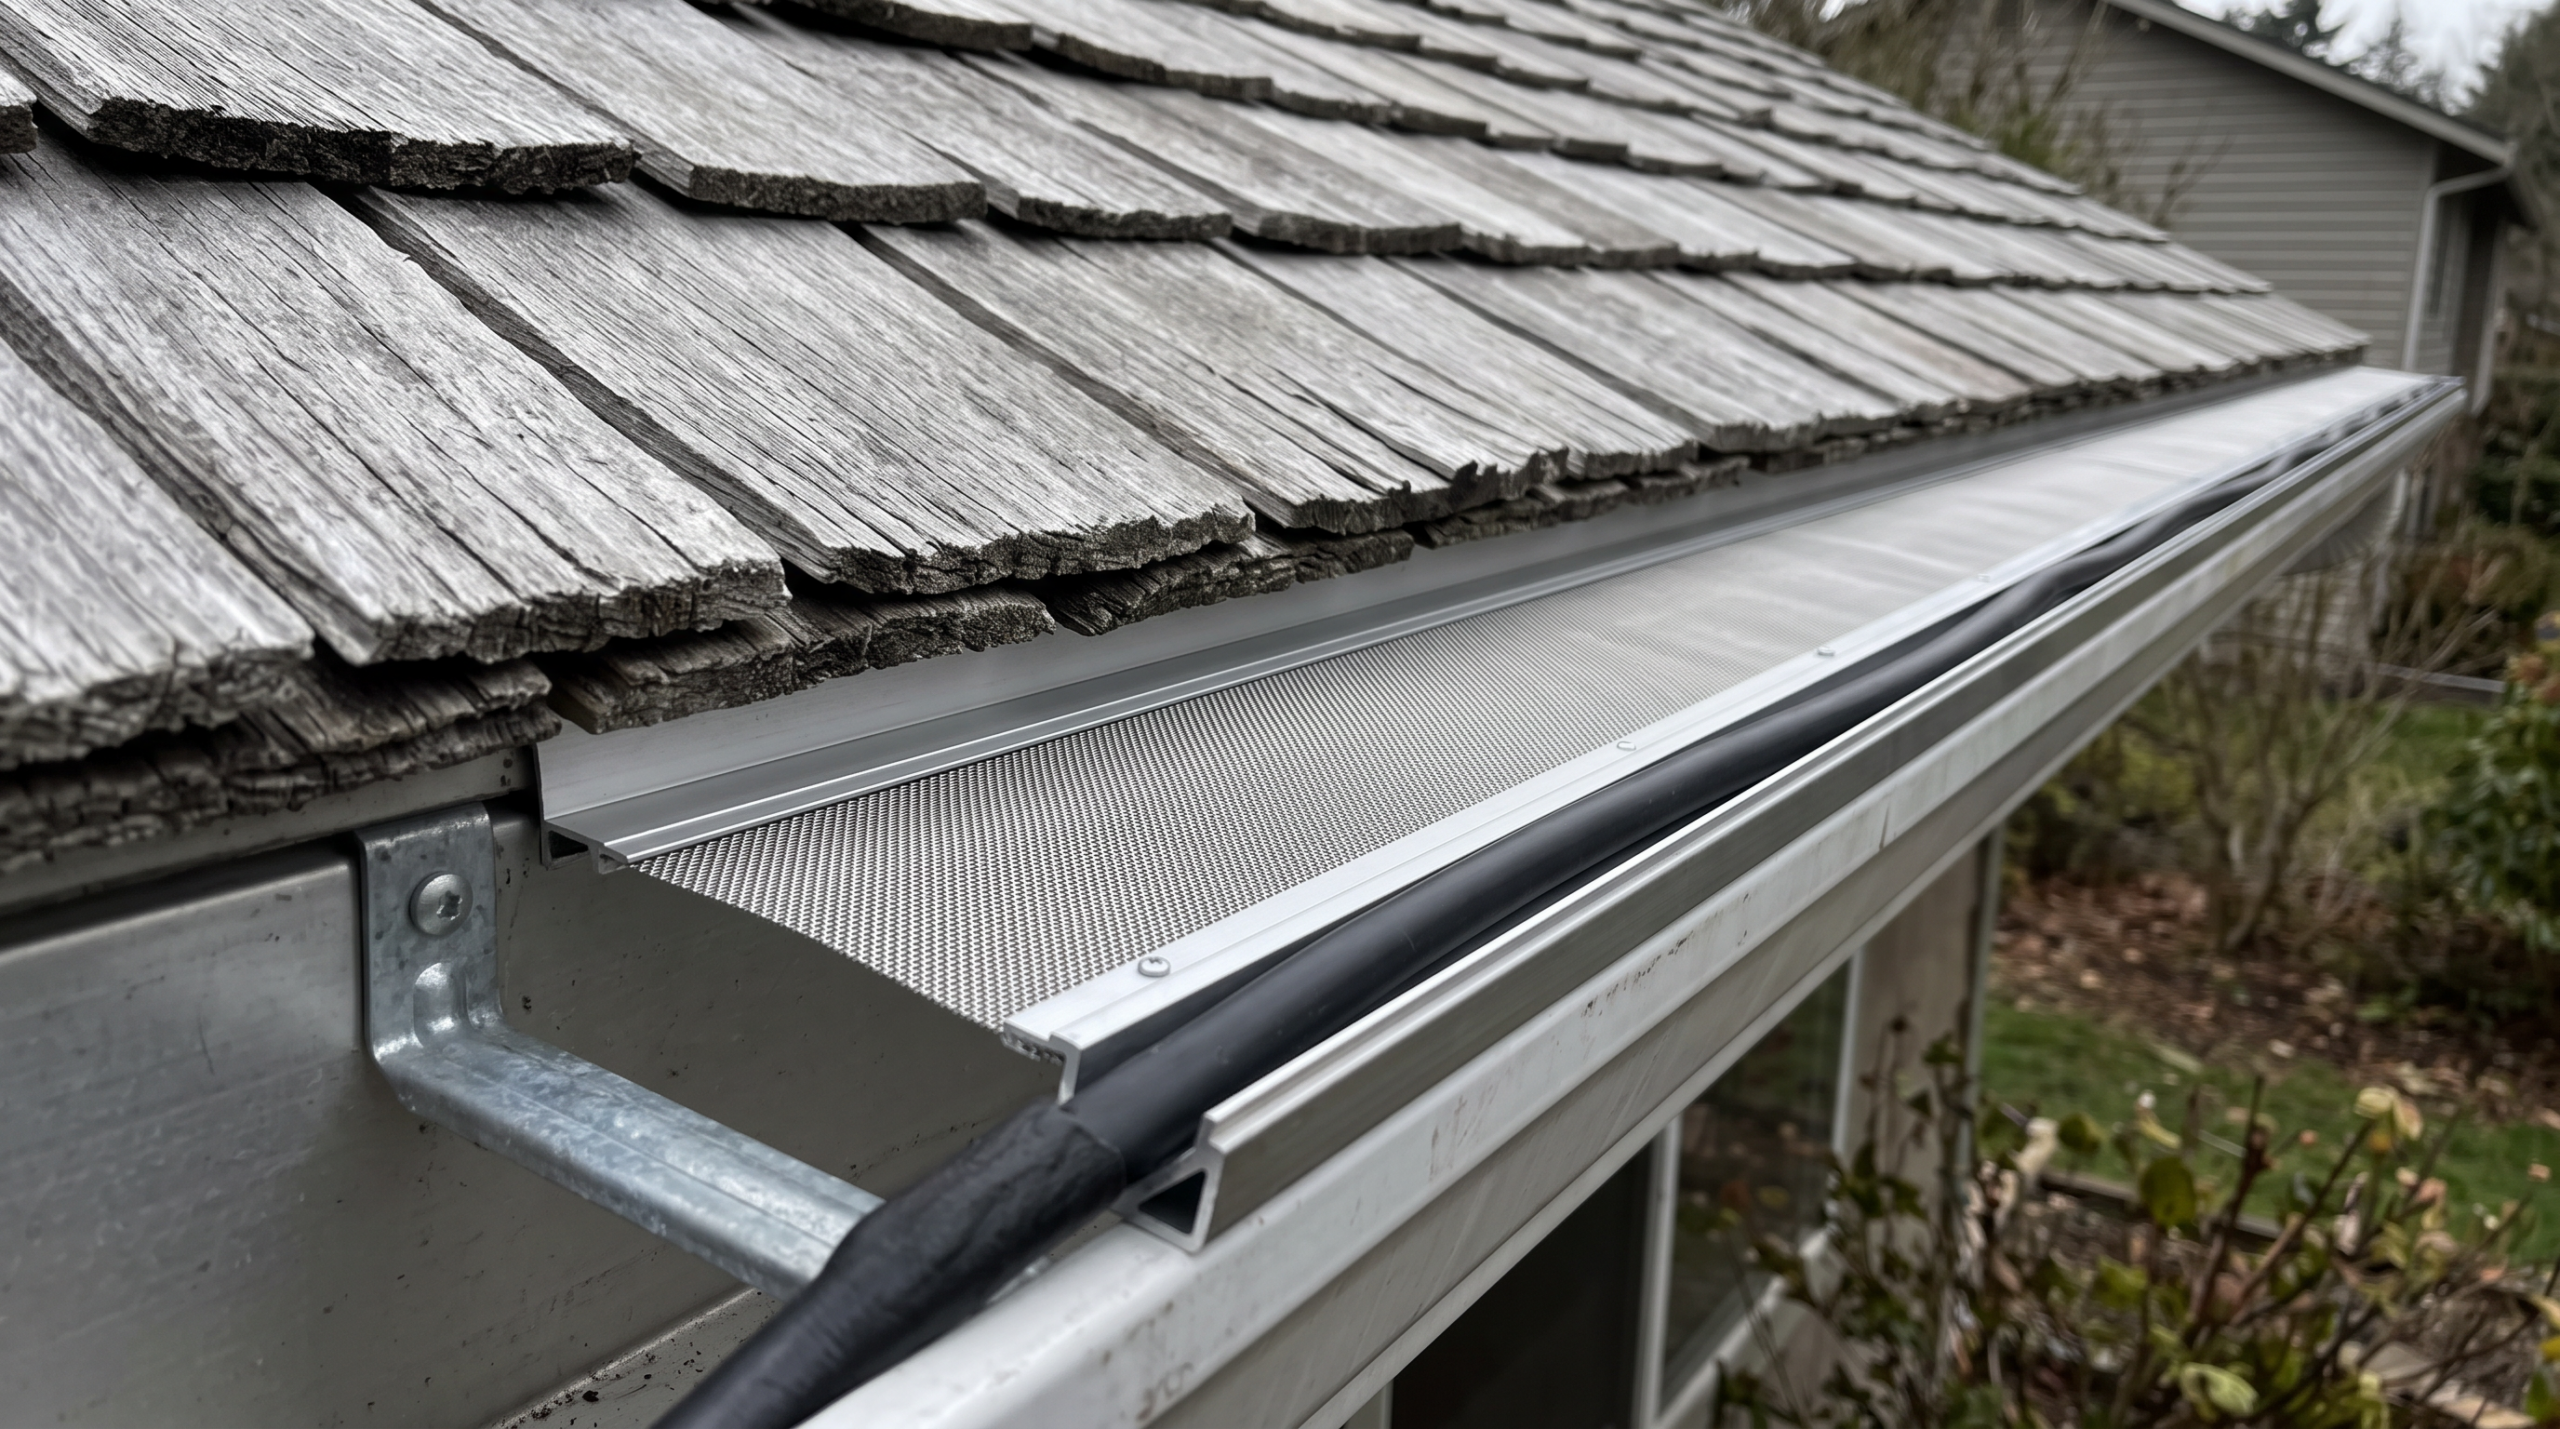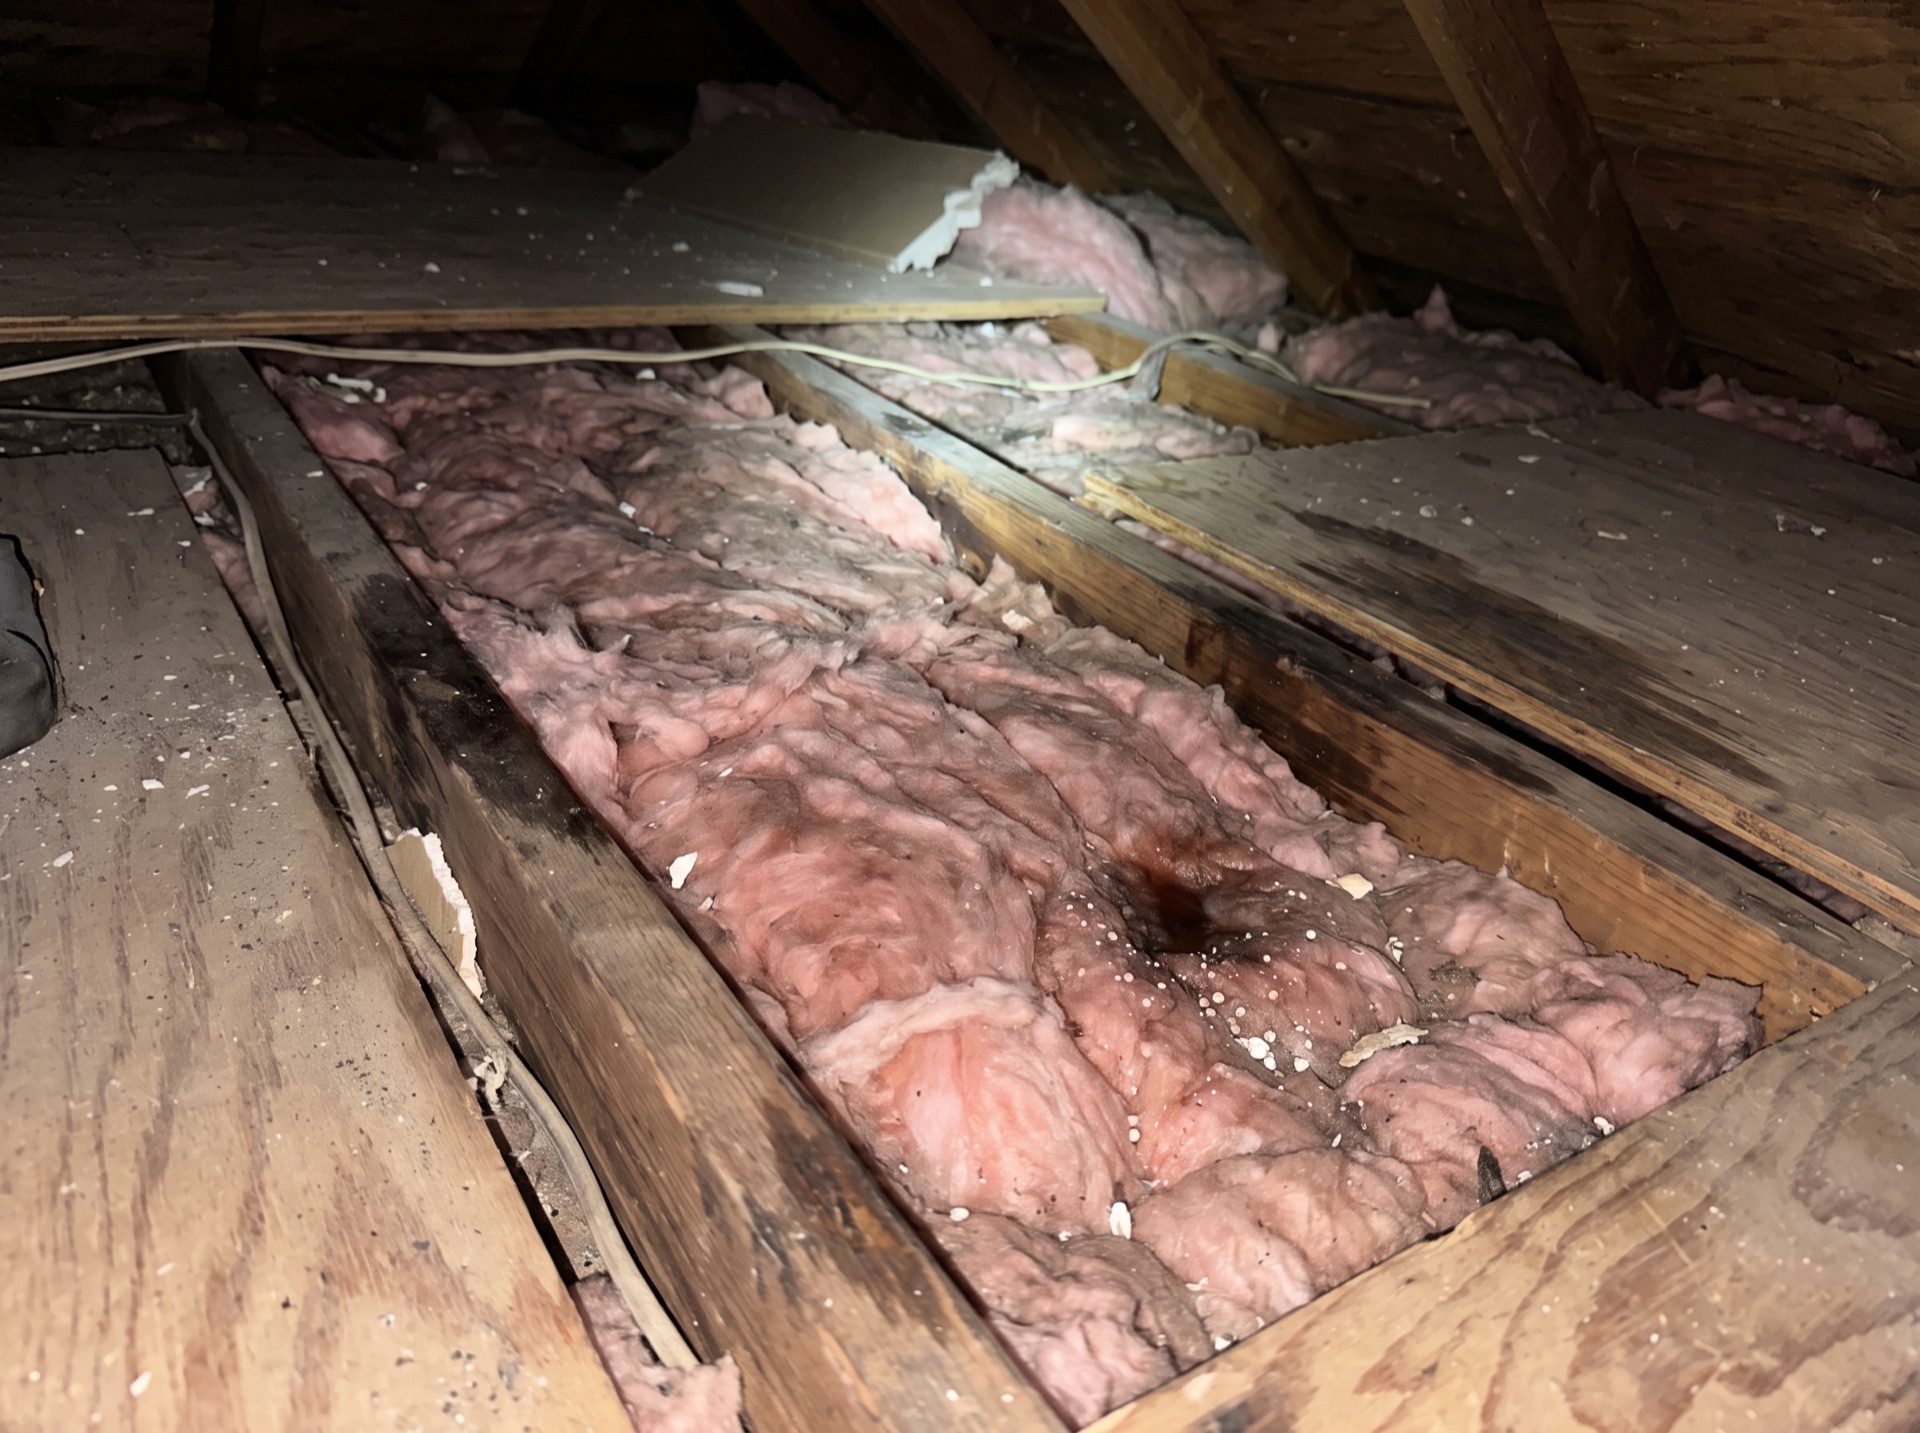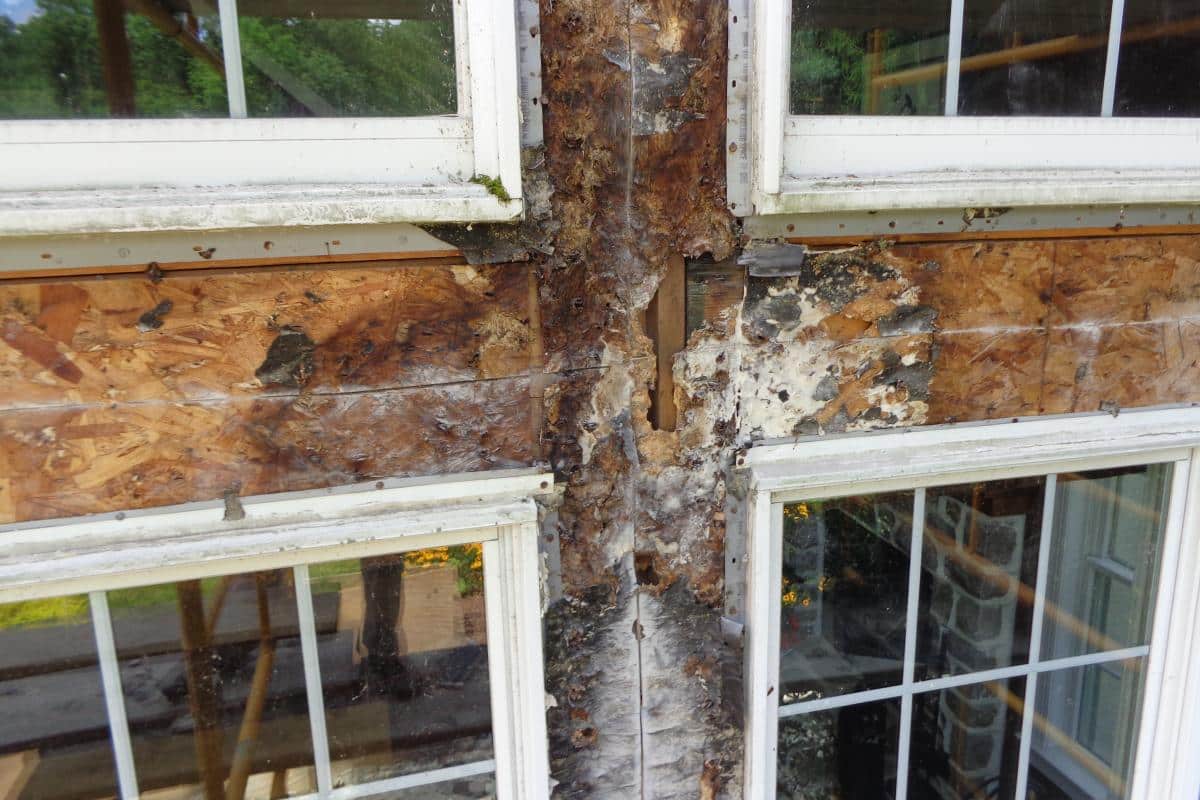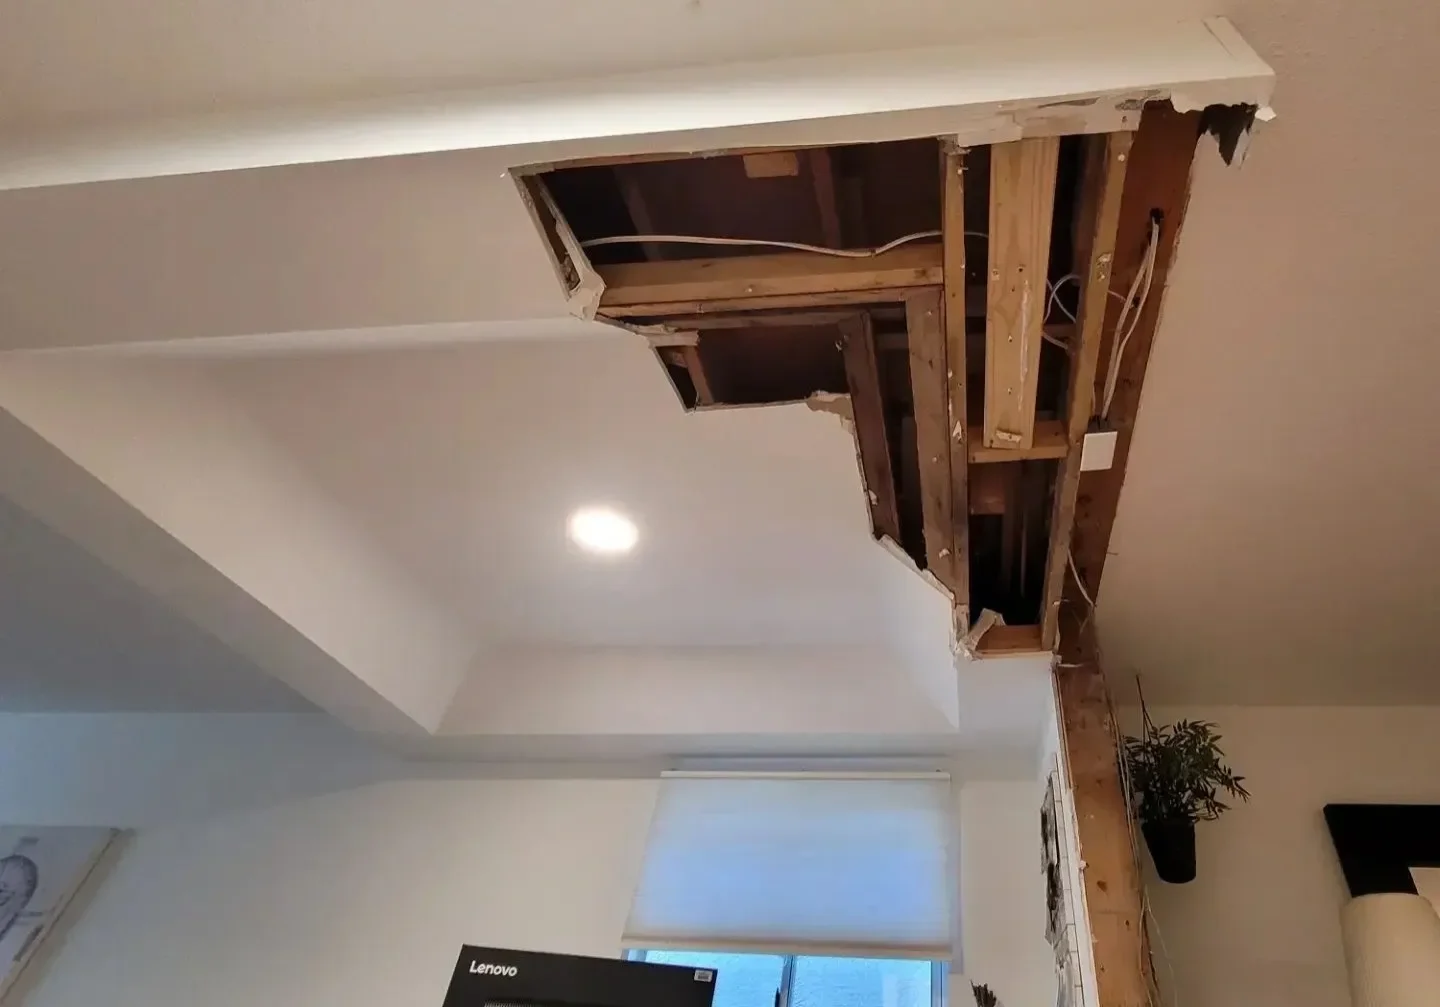
The ice along a roof in Pierreline is the symptom. The cause is warm air escaping into the attic, and it is still running right now. As part of our complete Pierre winter roof services, crews handle ice dam insurance claims across Hughes County.
Pierre Ice Dams and the Winter That Does Not Break
Snow that falls on a roof in Pierre in December tends to stay there. A pack that never fully clears is a pack that keeps feeding meltwater to the same eave for months on end.
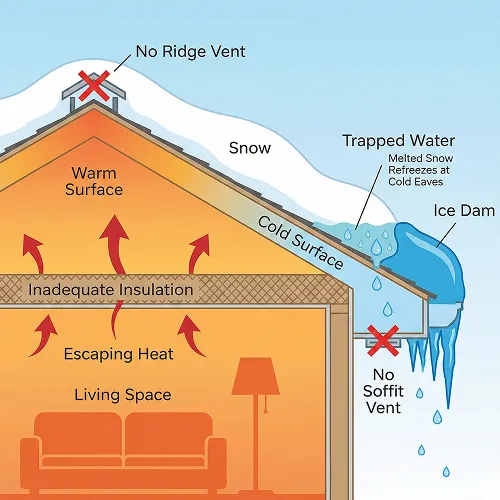
Depth accumulates faster than people expect because nothing in between melts it away. By February a Pierre eave can be carrying several hundred pounds of ice with standing water sitting behind the whole length of it.
Ice-barrier practice in Hughes County
In the colder South Dakota jurisdictions the membrane requirement extends well up the roof plane rather than stopping at the first course, precisely because the ice here does not stay near the edge.
Ice Dam Insurance Claims in Pierre: How The Work Runs
Why the time stamp on the photographs matters
An adjuster arriving in April is looking at a dry ceiling and a clear roof, and is being asked to accept an account of something that happened in January. Dated photographs taken while the ice was on the roof and the water was running are what turn that account into evidence. Does Insurance Pay for Ice Dam Water Damage?.
Crews photograph on arrival, during the work and on completion, with timestamps intact. It costs nothing at the time and it is routinely the difference between a paid claim and a contested one.
The roof on the same claim
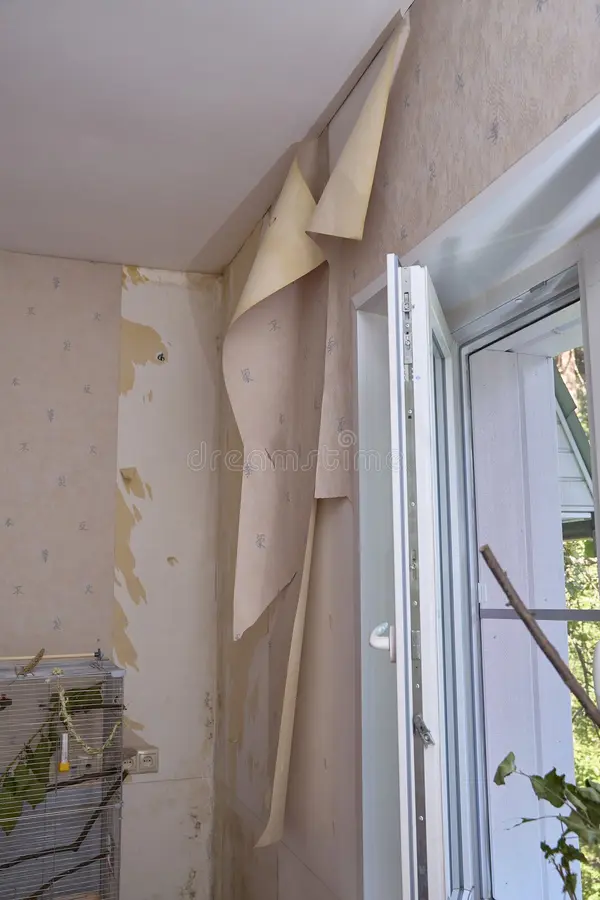
Ice dams can damage the roof itself: shingles lifted or cracked by ice, seal strips broken, underlayment and decking soaked and softened along the eave. Where that damage came from the storm event, it belongs on the same claim as the interior.
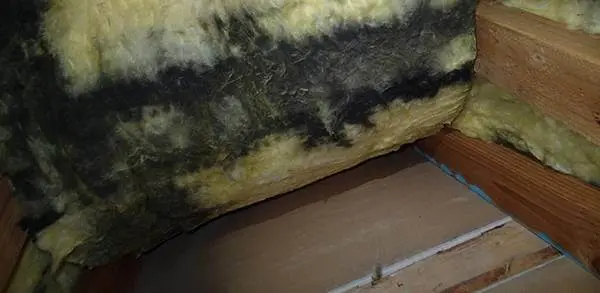
It does not cover a roof that was simply old. Photographs of the deck from the attic side, the shingles at the eave and the extent of the wet decking are what separate storm damage from wear.
Supplements: when the tear-out finds more
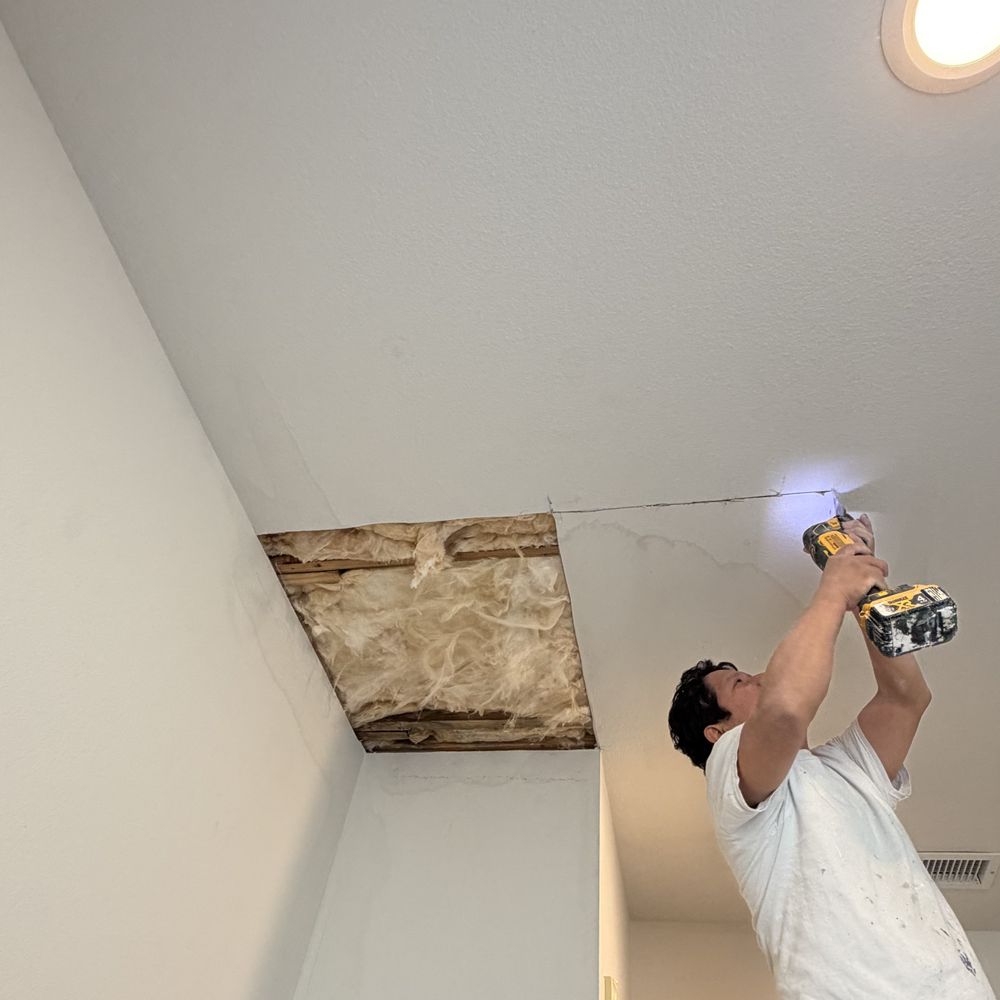
Scopes are written from what can be seen. Open a ceiling and the damage frequently runs further than the stain did, and the original estimate no longer covers the work.
That is a supplement, and it is ordinary. What makes it go smoothly is photographs of the newly exposed damage, a revised line-item scope, and raising it when it is found rather than at the end. Work carried out before the carrier has seen it is the version that tends to go unpaid.
What a carrier is actually looking for
A claim turns on proving sudden, accidental water intrusion rather than a maintenance failure the homeowner let develop. In practice that means dated photographs of the dam, the entry points and the interior damage, taken while the event is live — not reconstructed in March from memory.
Crews photograph as they work for exactly this reason. Timestamped images of the ice before removal, the water path, the affected interior and the dried-out result form the spine of a claim that survives review.
Scopes in the format adjusters use
Scopes get written in Xactimate line items, with the mitigation work priced and described the way a carrier's own estimating software describes it. An adjuster comparing like to like approves faster than one translating a hand-written invoice into their system.
Where the policy allows direct billing, carriers are billed directly, so the out-of-pocket conversation is smaller from the start.
What you get in Pierre
- One claim for the whole eventRemoval, mitigation, mold, interior repair and roof on a single file
- Roof replacement scopedWhere the ice dam damaged shingles or decking, the roof goes on the same claim
- Direct billingCarriers billed directly wherever the policy allows it
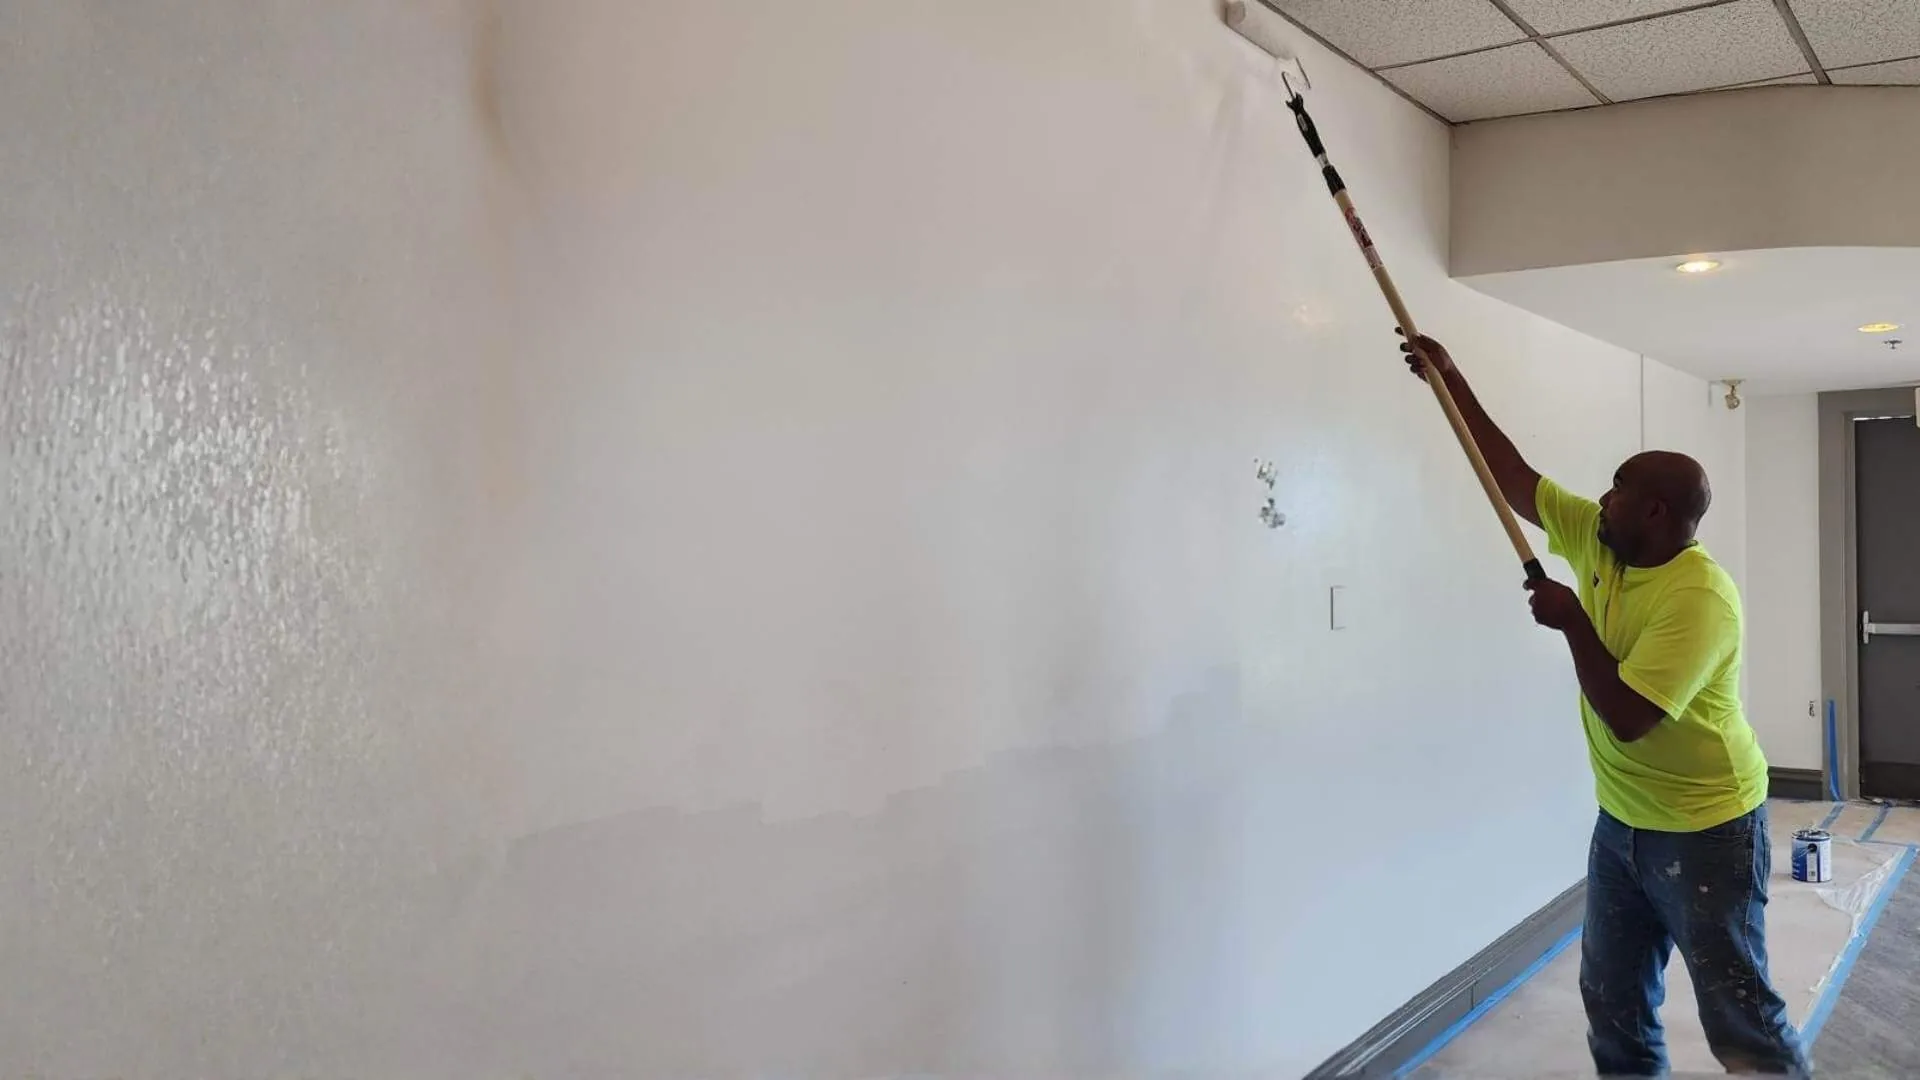
| Interior repair | Insulation, drywall, texture, trim and paint, done in-house after drying |
|---|---|
| Documentation | Dated before and after photos, written scope in Xactimate line items |
| Method | Containment, HEPA filtration and drying to a measured IICRC standard |
| Local ice-barrier practice | Eave membrane required on new work |
| Dispatch window | Same day to 24 hours |
| Coverage area | Pierre and Hughes County |
| Primary climate stressor | Sustained sub-freezing, long season |
Neighborhoods and Towns We Reach From Pierre
Crews working Pierre cover the adjoining communities on the same route — Fort Pierre — so a storm week usually means one truck handling several addresses in Hughes County rather than separate trips.
Nearest hub towns with their own insurance claims pages: Aberdeen, Mitchell, Rapid City, Watertown, Deadwood, Brookings.
Scheduling for Pierre tightens up during a freeze event, which is exactly when the phone beats the form. Water coming in means a call, not an email.
Most jobs do not stop at one service. Insurance Claims in Pierre often runs alongside water mitigation & dryout in Pierre, and both get written into one scope rather than billed as separate visits.
Active leak right now? Our 24/7 Pierre steam ice dam removal crews are dispatched first during a freeze event. Call (888) 561-9664.