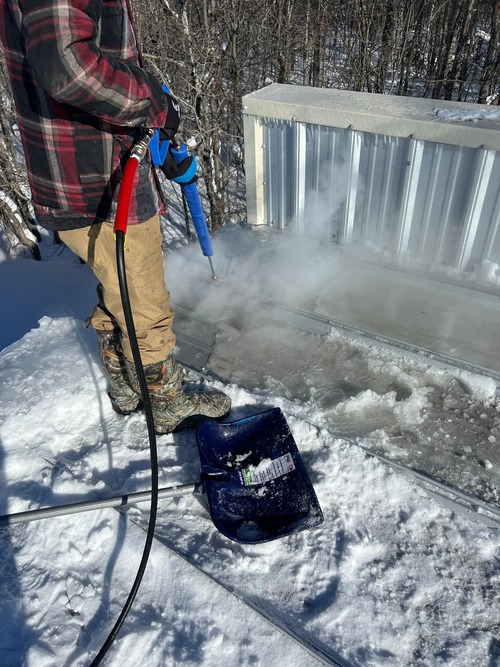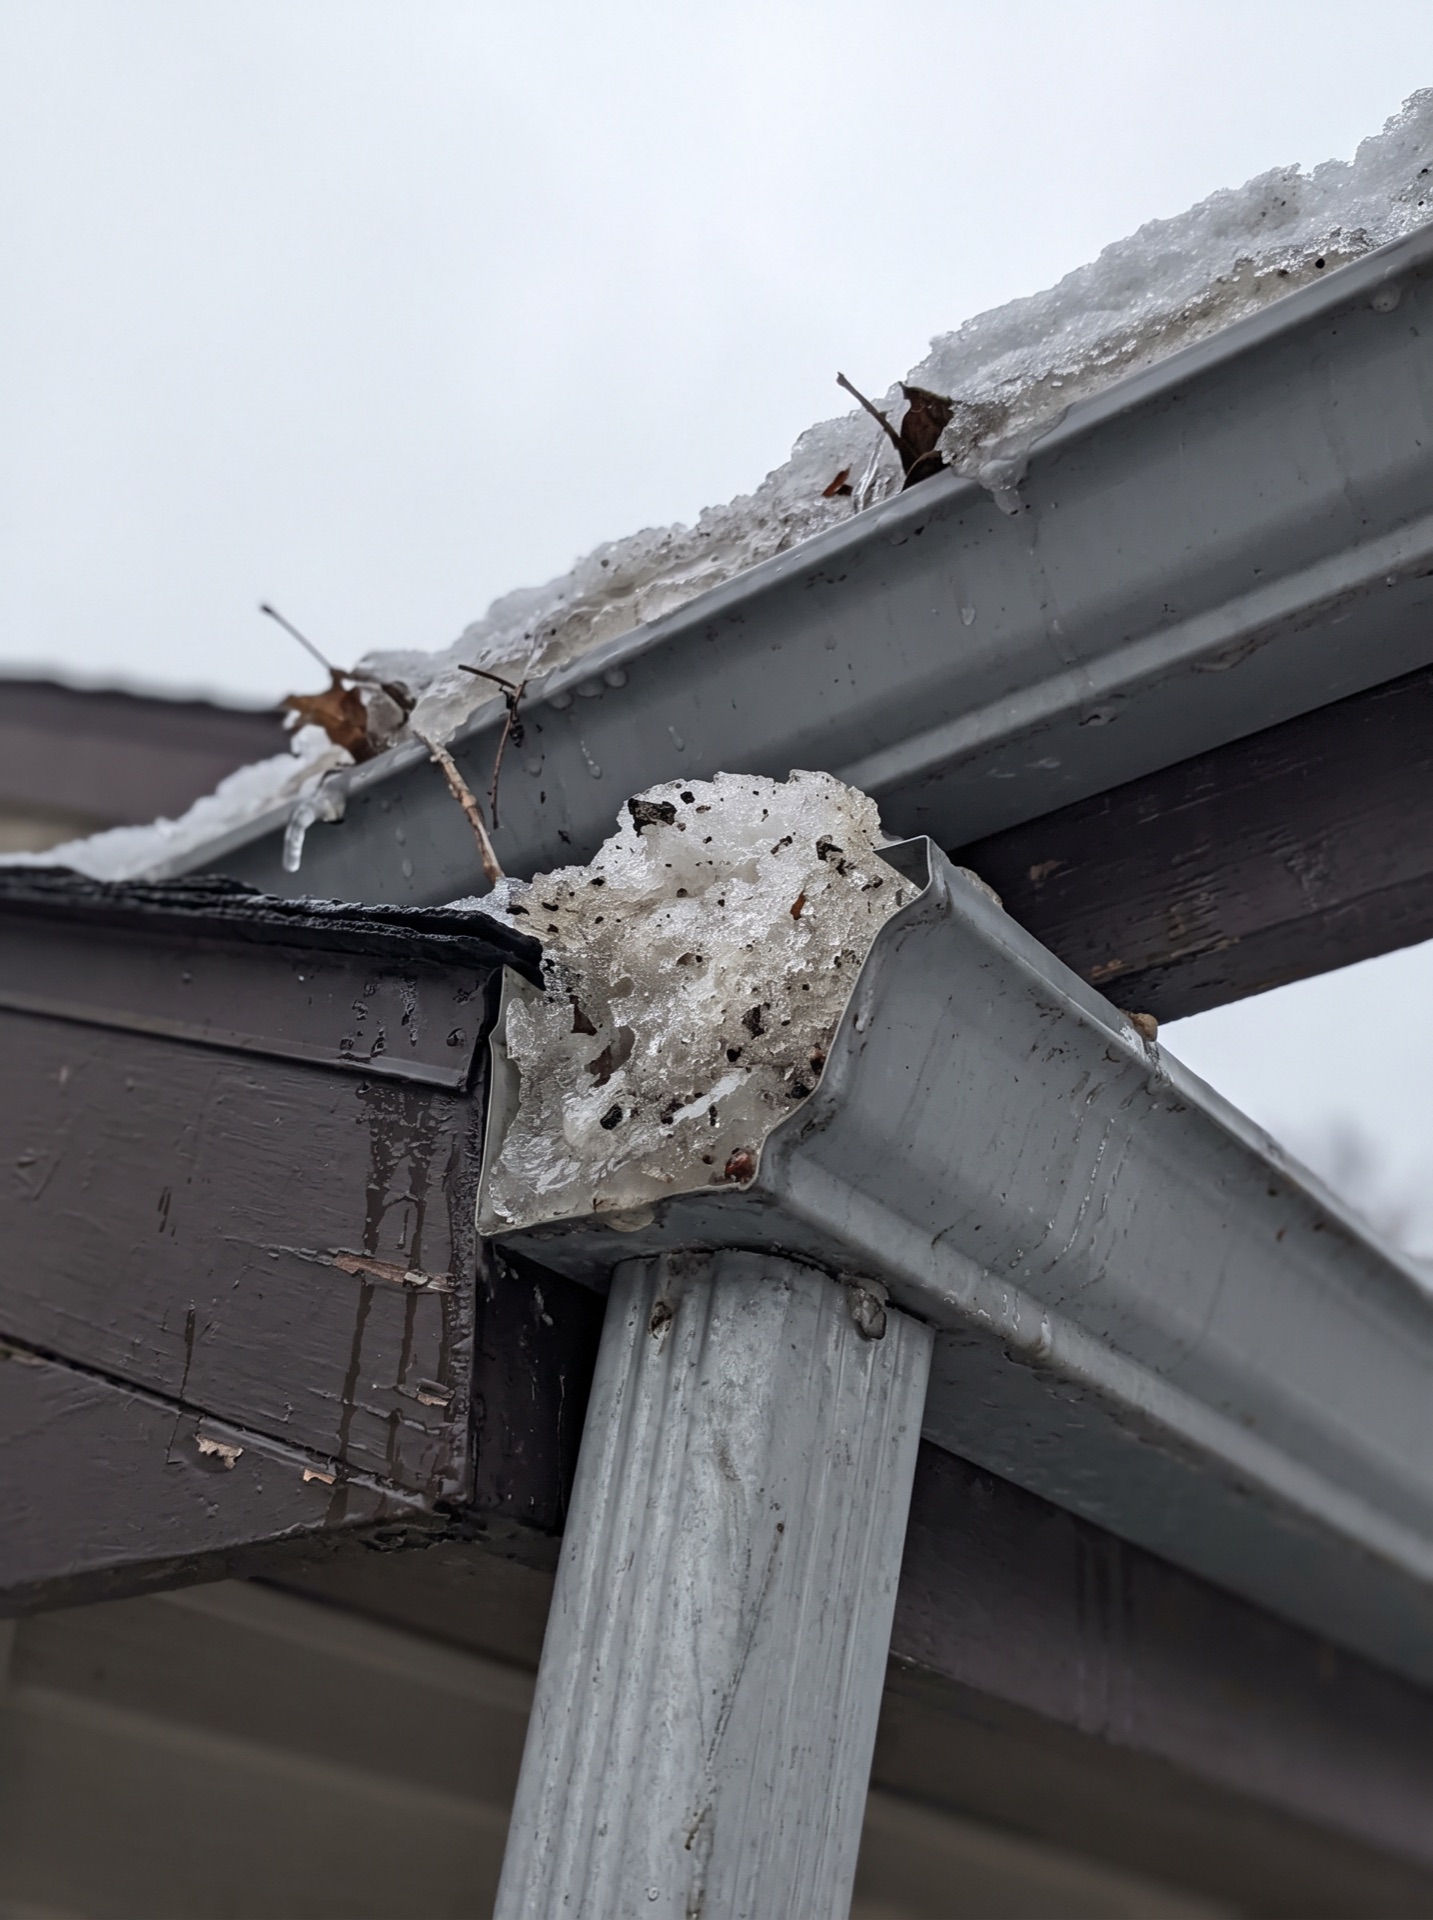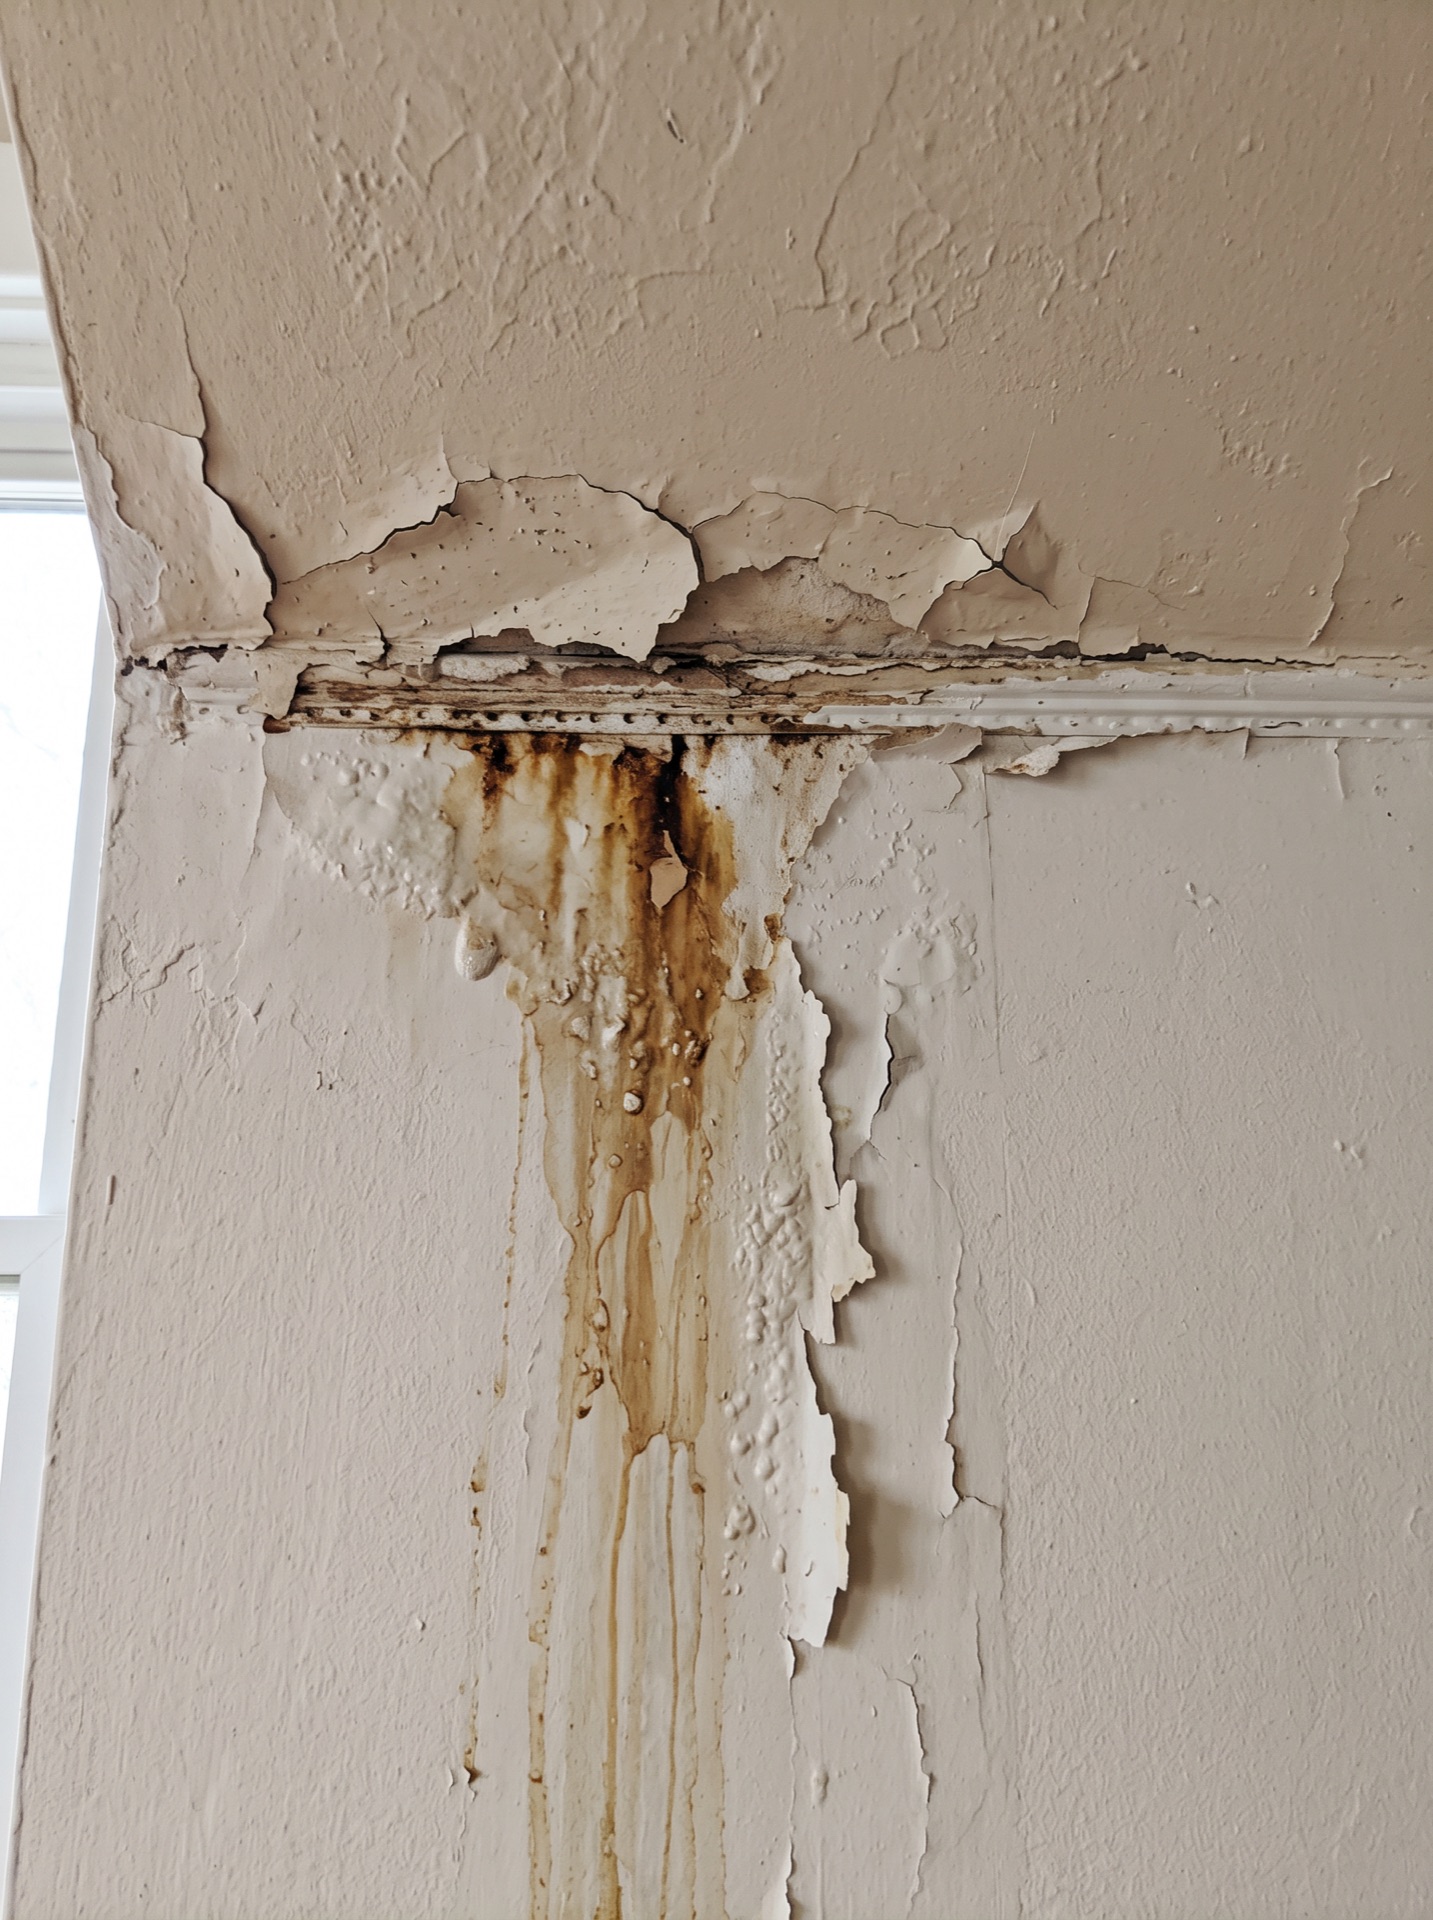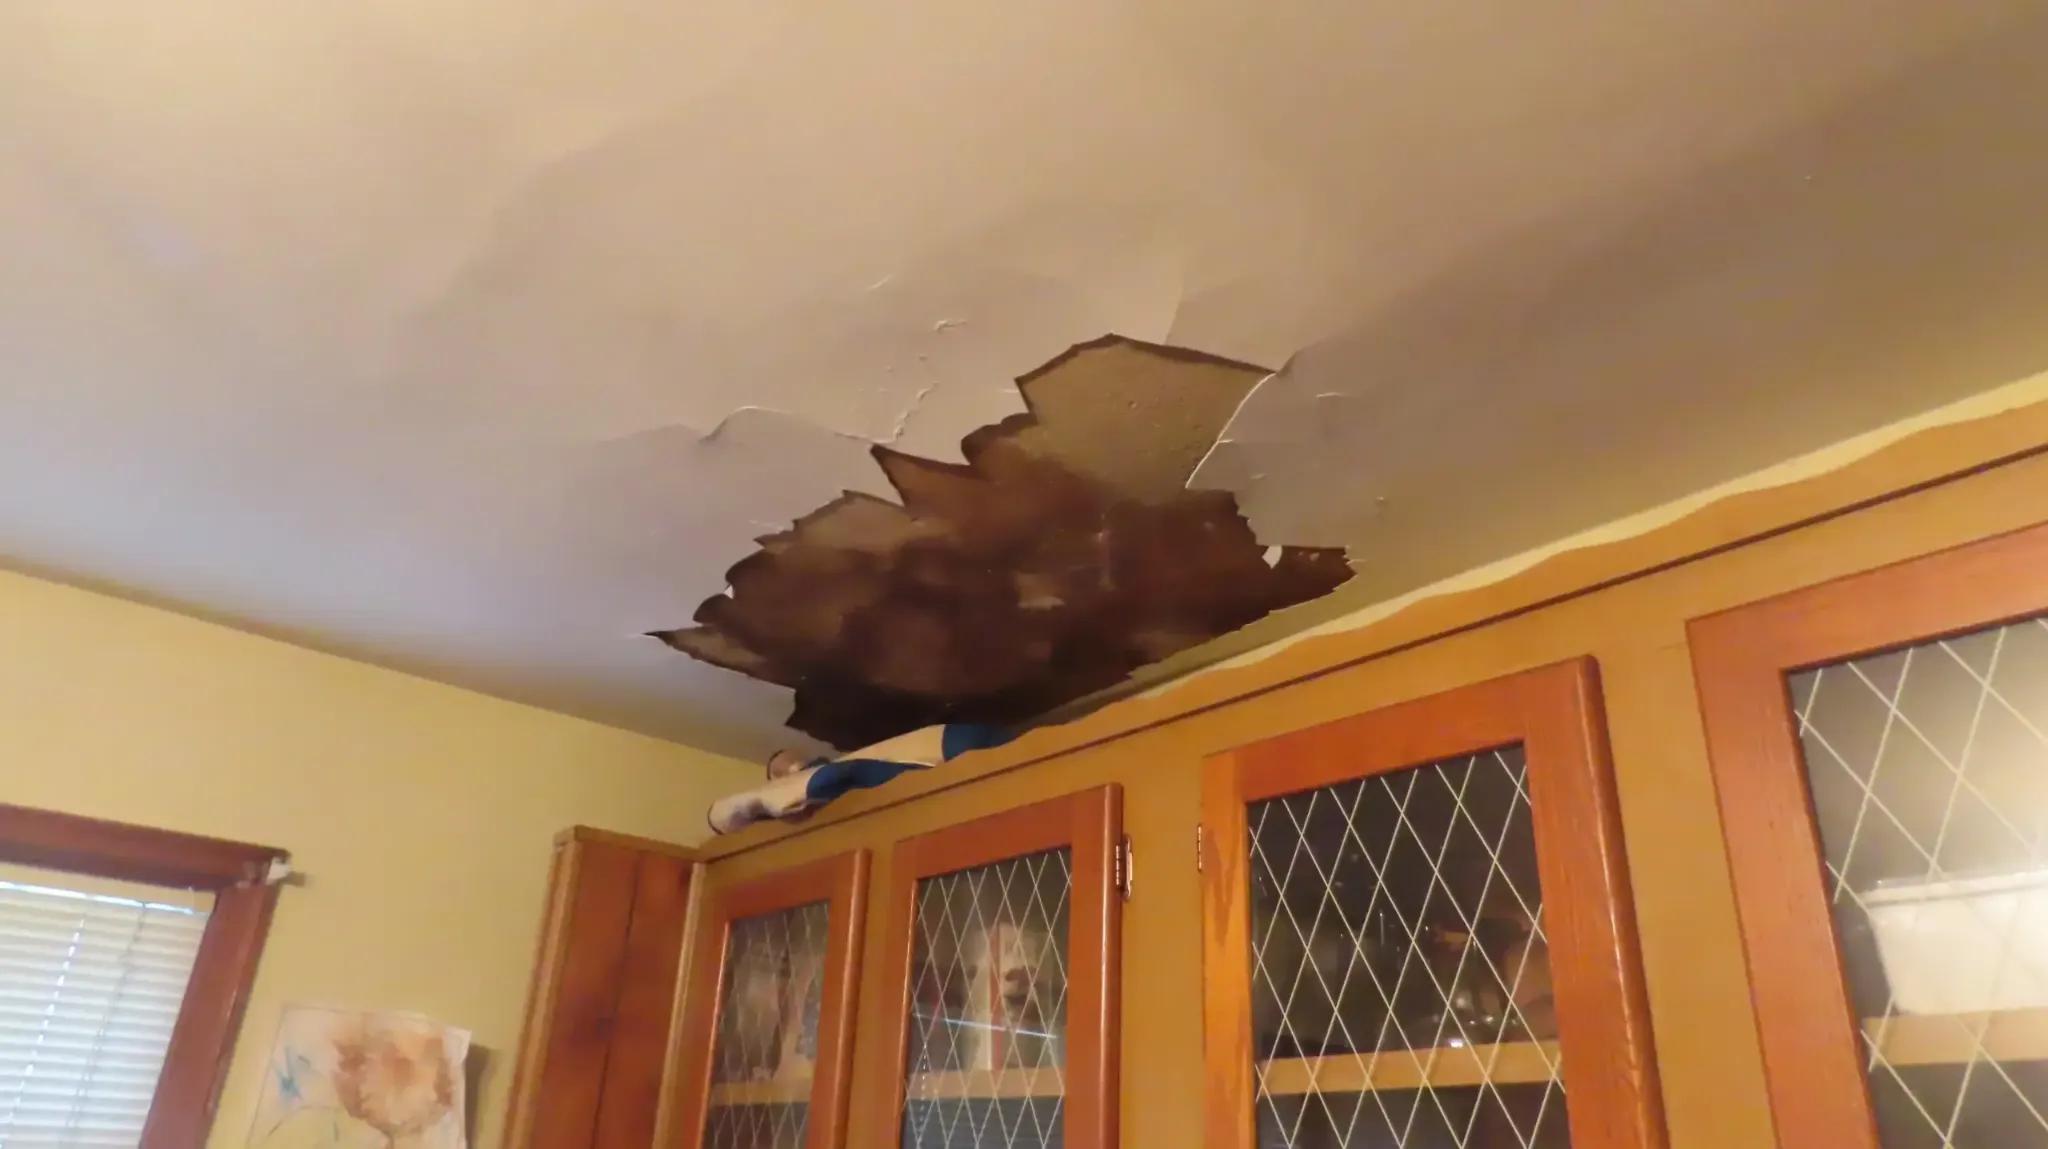
Scott County sees the same pattern every winter: snow on the roof, warm air in the attic, and a line of ice building along the eave where the two meet. As part of our complete Savage winter roof services, crews handle ice dam insurance claims across Scott County.
Why Savage Roofs Dam Up: Lake-Effect Load and Freeze-Thaw
What makes Scott County roofs dam is not the seasonal total, it is how the snow arrives. Bands dump a heavy, saturated pack in hours, and that pack becomes a water reservoir sitting on a heated surface.
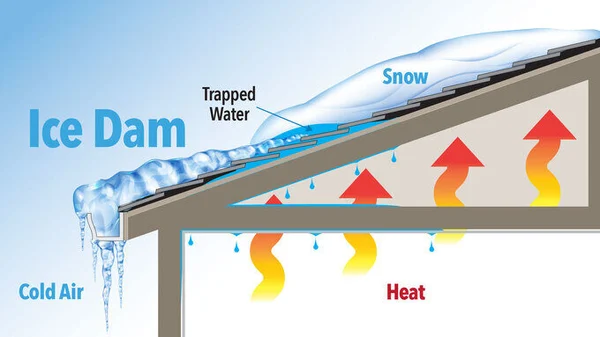
The damage comes on the thaw. Warm air leaking into the attic melts the underside of that pack, the meltwater runs to an eave that is still well below freezing, and it sets. Repeat that four or five times in a January and the ridge of ice at the gutter line stops being cosmetic.
Ice-barrier practice in Scott County
The relevant detail is how far up the roof the membrane runs — it has to reach past the interior wall line, not just cover the first course. On older Savage roofs it frequently does neither.
Ice Dam Insurance Claims in Savage: How The Work Runs
One claim, broken out by coverage
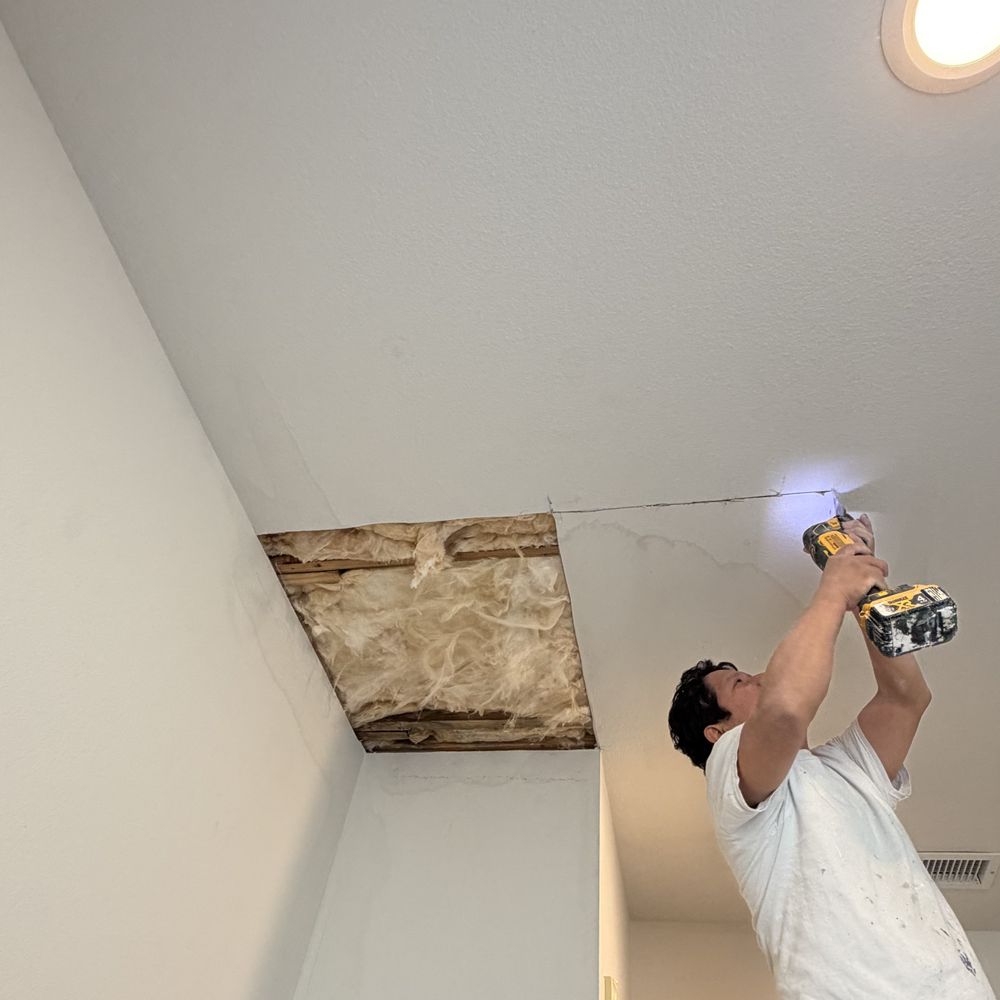
Everything an ice dam caused goes on one claim, but not as one lump number. Emergency removal and dryout are loss mitigation. Mold remediation often sits under its own sublimit. Interior repair and the roof sit under dwelling coverage. Does Insurance Pay for Ice Dam Water Damage?.
Writing the scope with those lines separated is what lets an adjuster approve each part on its own terms, and it stops a dispute over one line holding up the rest of a Savage claim.
The roof on the same claim
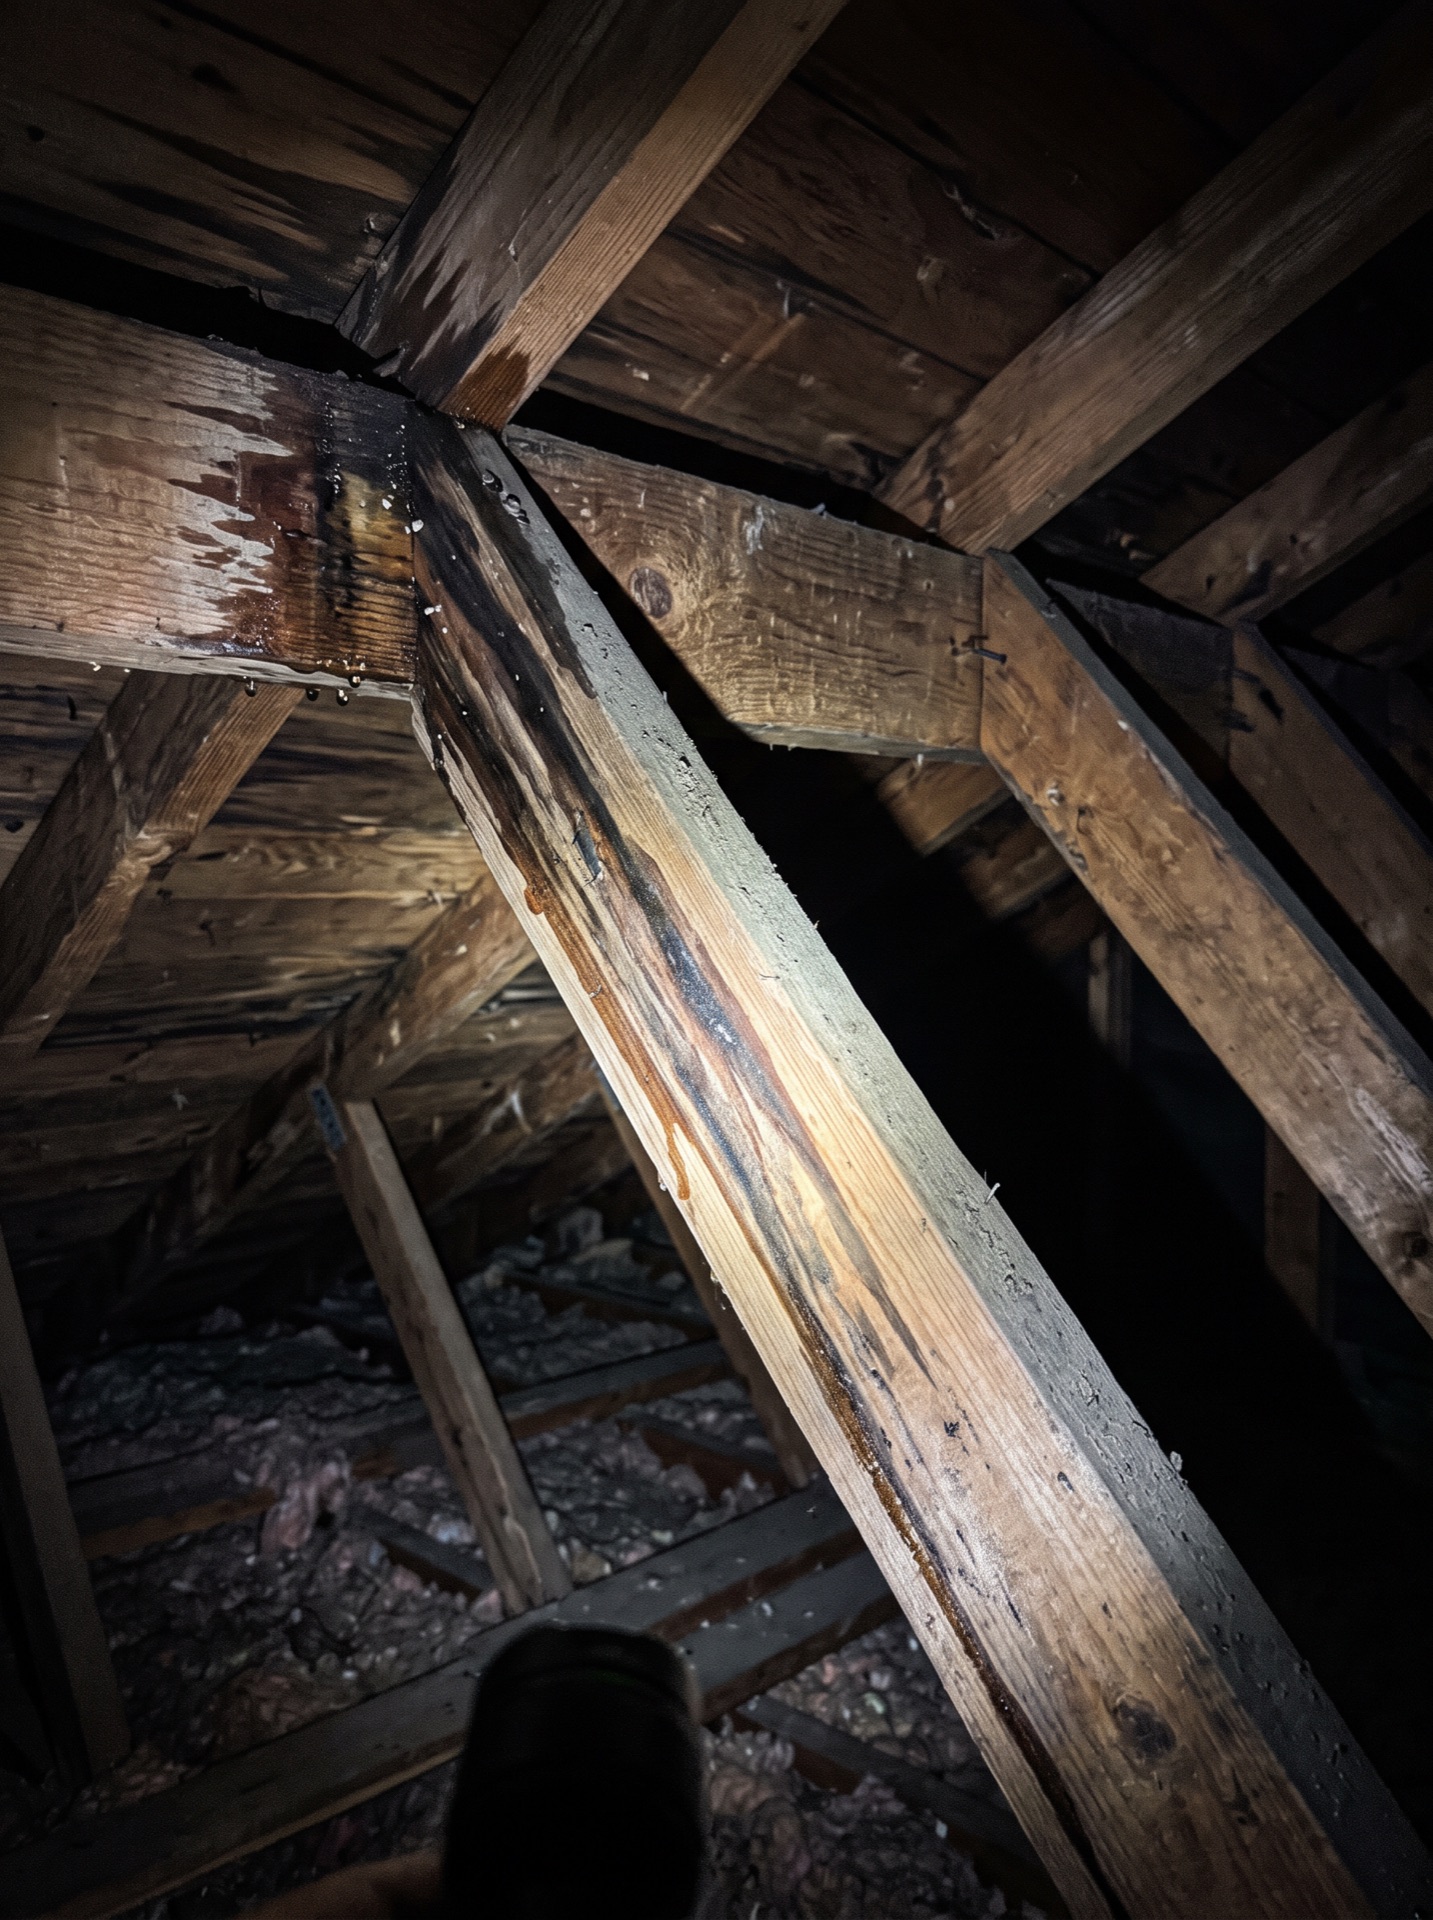
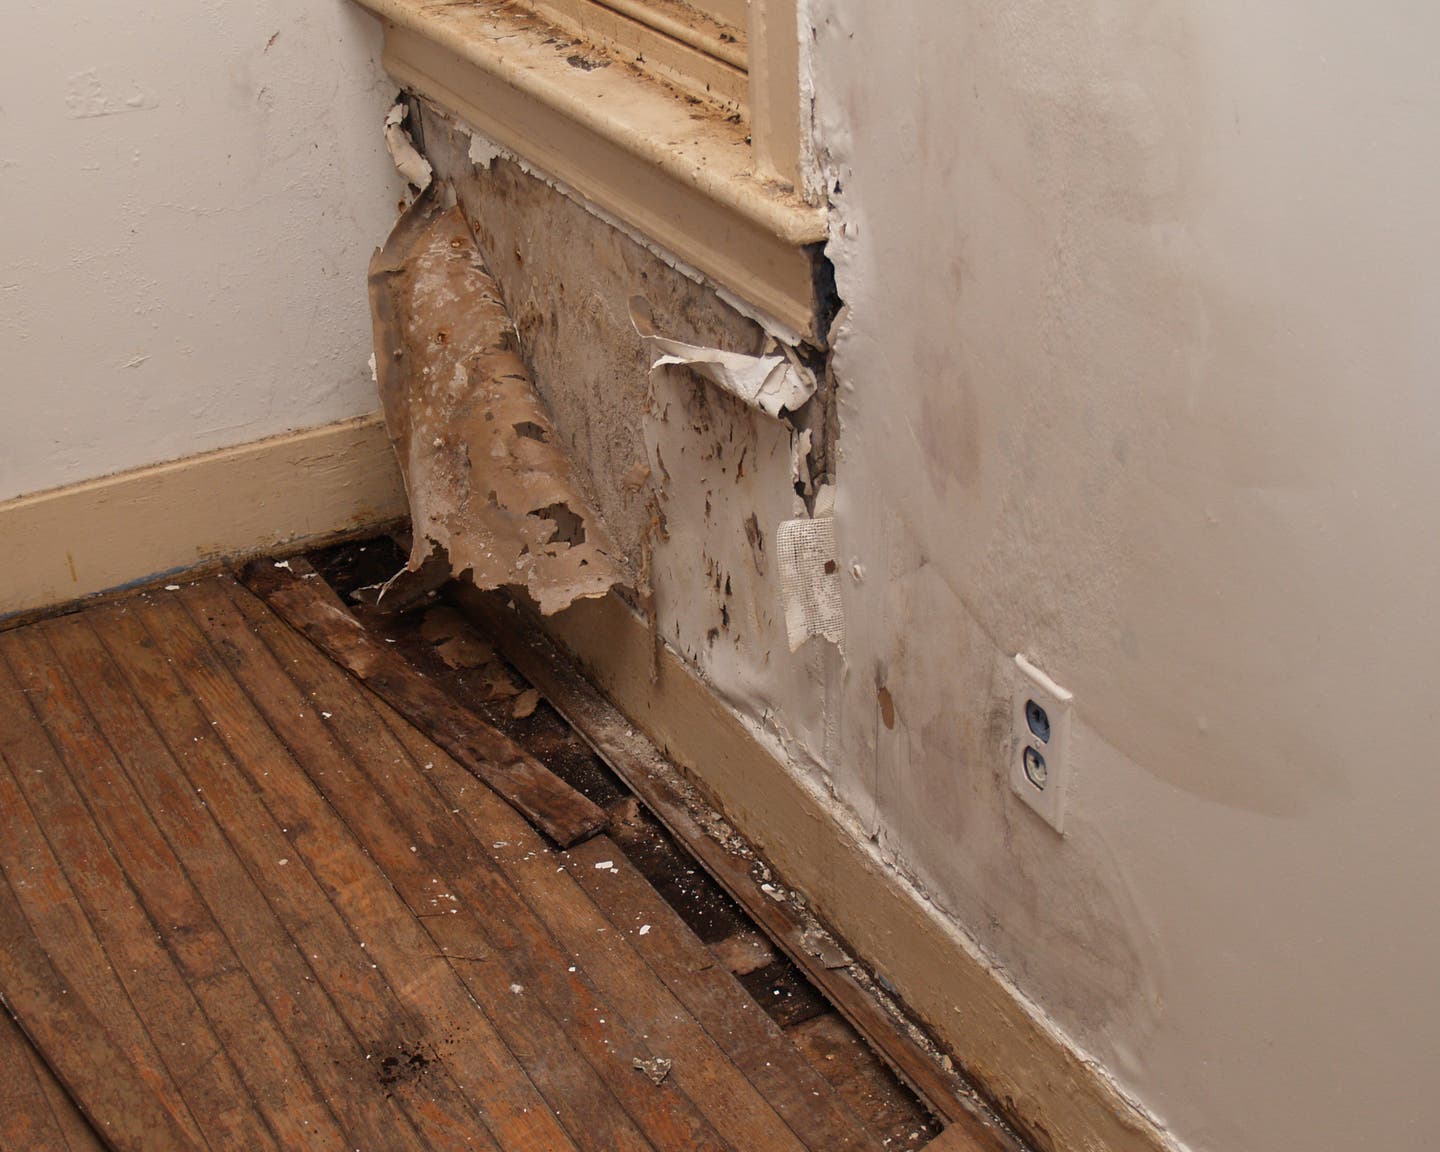
Ice dams can damage the roof itself: shingles lifted or cracked by ice, seal strips broken, underlayment and decking soaked and softened along the eave. Where that damage came from the storm event, it belongs on the same claim as the interior.
It does not cover a roof that was simply old. Photographs of the deck from the attic side, the shingles at the eave and the extent of the wet decking are what separate storm damage from wear.
Replacement cost, actual cash value and the second check
Most policies pay the depreciated value first and release the remainder once the repair is actually completed and invoiced. People who do not know that see the first check, assume it is the whole settlement, and decide the claim was not worth filing.
Reading which of those two your policy is on, before the work is scoped, changes what gets claimed and when. The specifics are between you and your carrier - what a contractor supplies is the documentation each stage needs.
Why the scope gets written in Xactimate line items
Most carriers estimate in Xactimate. A scope that already speaks that language can be compared line for line instead of translated, and translation is where hours get cut.
It does not guarantee the number. It removes one of the common reasons a reasonable number gets reduced.
What a maintenance-exclusion denial actually argues
The carrier's position is that the dam built up gradually and could have been prevented, making it maintenance rather than a sudden accidental event. Put that way it is hard to argue with in the abstract.
It is much harder to sustain against dated photographs of a specific storm event, a written scope describing the intrusion, and moisture readings taken while the water was still there. That is the counter, and it has to be collected at the time.
What you get in Savage
- One claim for the whole eventRemoval, mitigation, mold, interior repair and roof on a single file
- Xactimate line itemsScopes written in the carrier's own estimating language
- Adjuster meetingsCrews meet the adjuster on site and walk the damage with them
| Primary climate stressor | Lake-effect bands, wet heavy pack |
|---|---|
| Billing | Xactimate line items on one claim; carrier billed directly where the policy allows |
| Documentation | Dated before and after photos, written scope in Xactimate line items |
| Dispatch window | Same day to 24 hours |
| Local ice-barrier practice | Eave membrane expected on re-roofs |
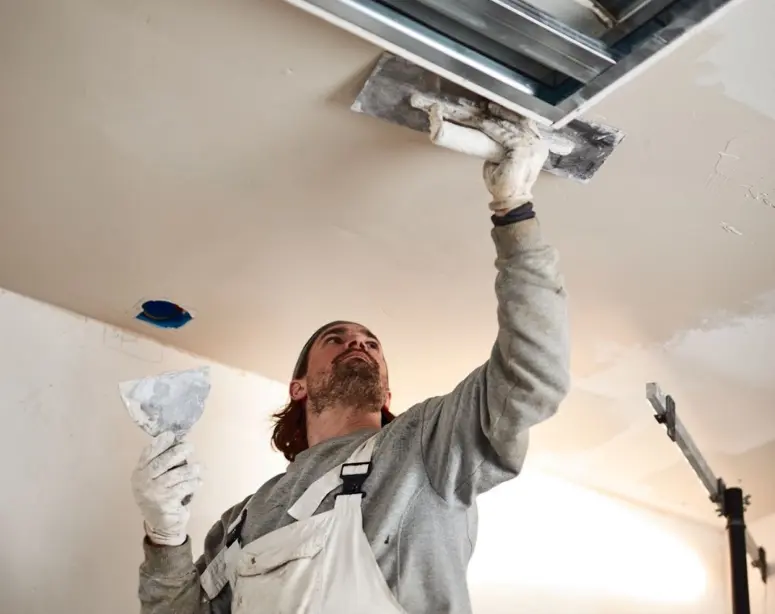
| Interior repair | Insulation, drywall, texture, trim and paint, done in-house after drying |
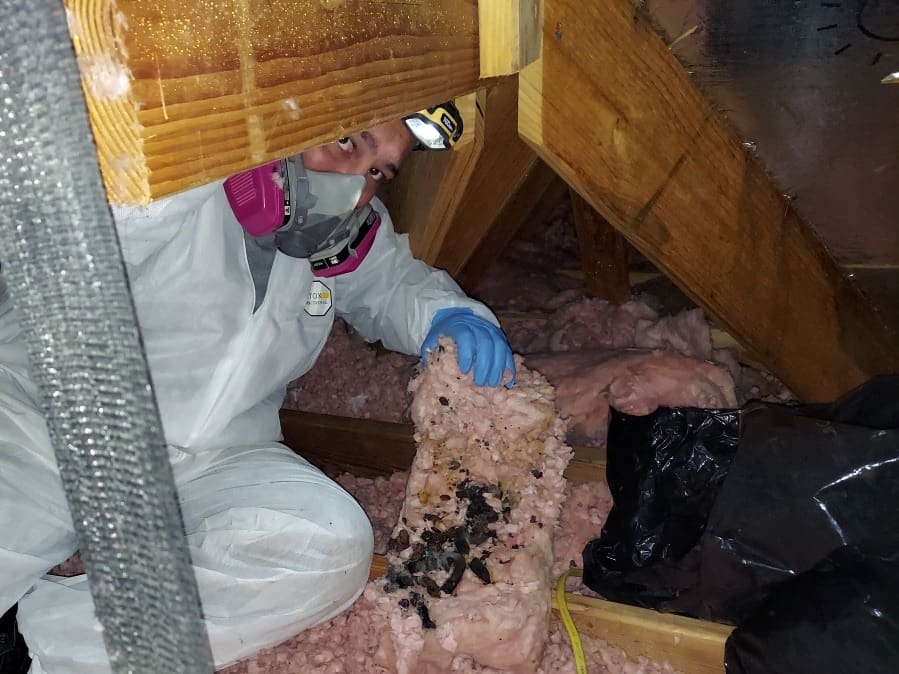
| Method | Containment, HEPA filtration and drying to a measured IICRC standard |
Neighborhoods and Towns We Reach From Savage
Crews working Savage cover the adjoining communities on the same route — Saint Louis Park, Elko, Mendota and New Market — so a storm week usually means one truck handling several addresses in Scott County rather than separate trips.
Nearest hub towns with their own insurance claims pages: Burnsville, Prior Lake, Bloomington, Apple Valley, Lakeville, Eden Prairie.
When a storm hits Scott County, crews are dispatched by severity rather than by call order — water already inside the house goes first.
Most jobs do not stop at one service. Insurance Claims in Savage often runs alongside water mitigation & dryout in Savage, and both get written into one scope rather than billed as separate visits.
Active leak right now? Our 24/7 Savage steam ice dam removal crews are dispatched first during a freeze event. Call (888) 561-9664.