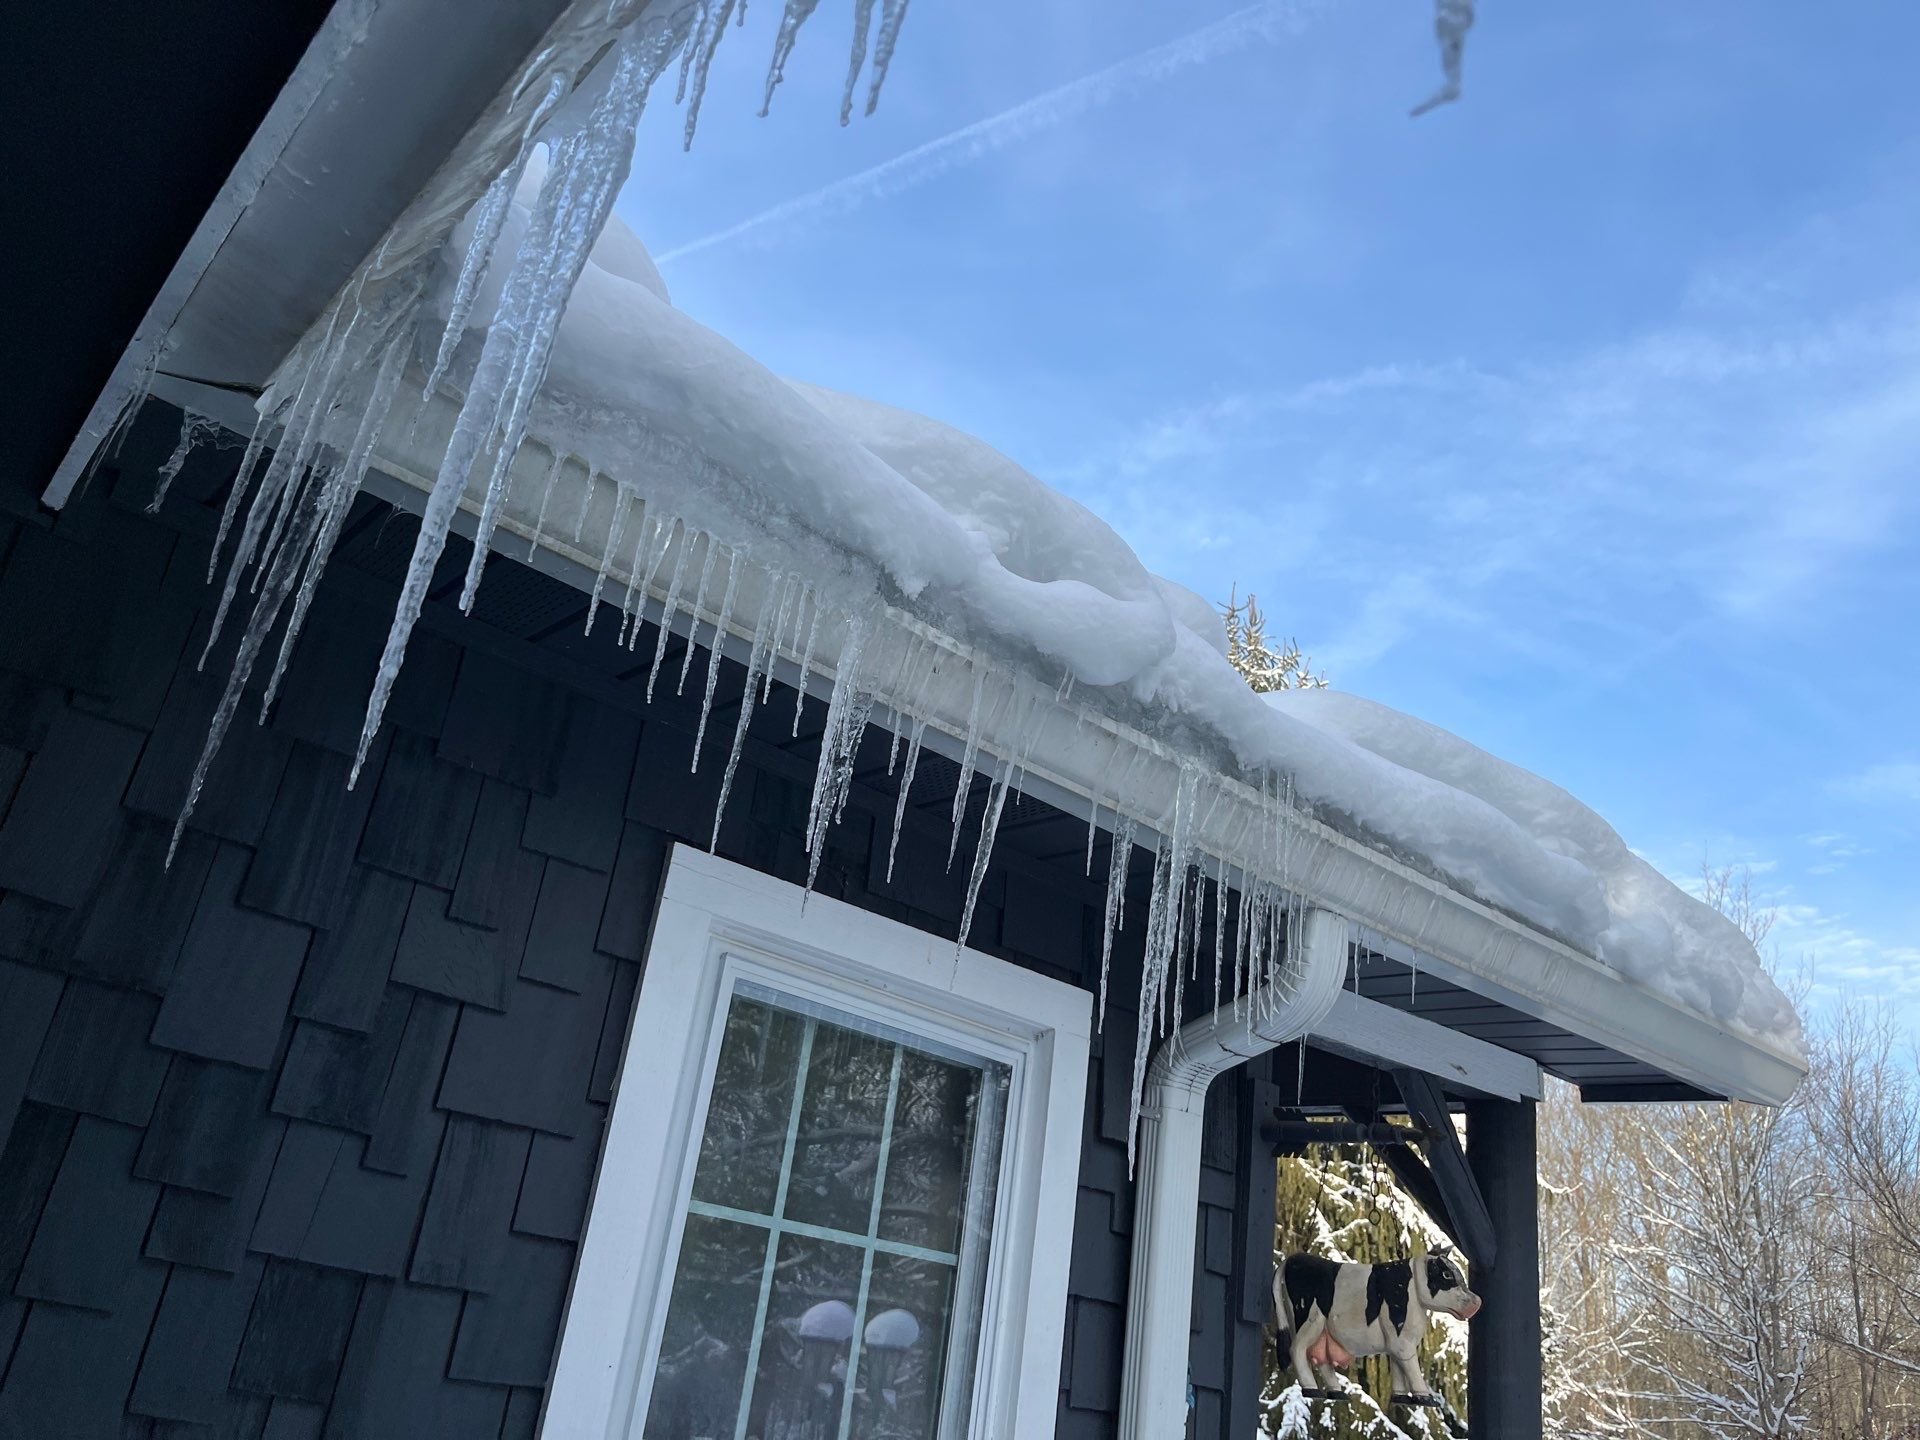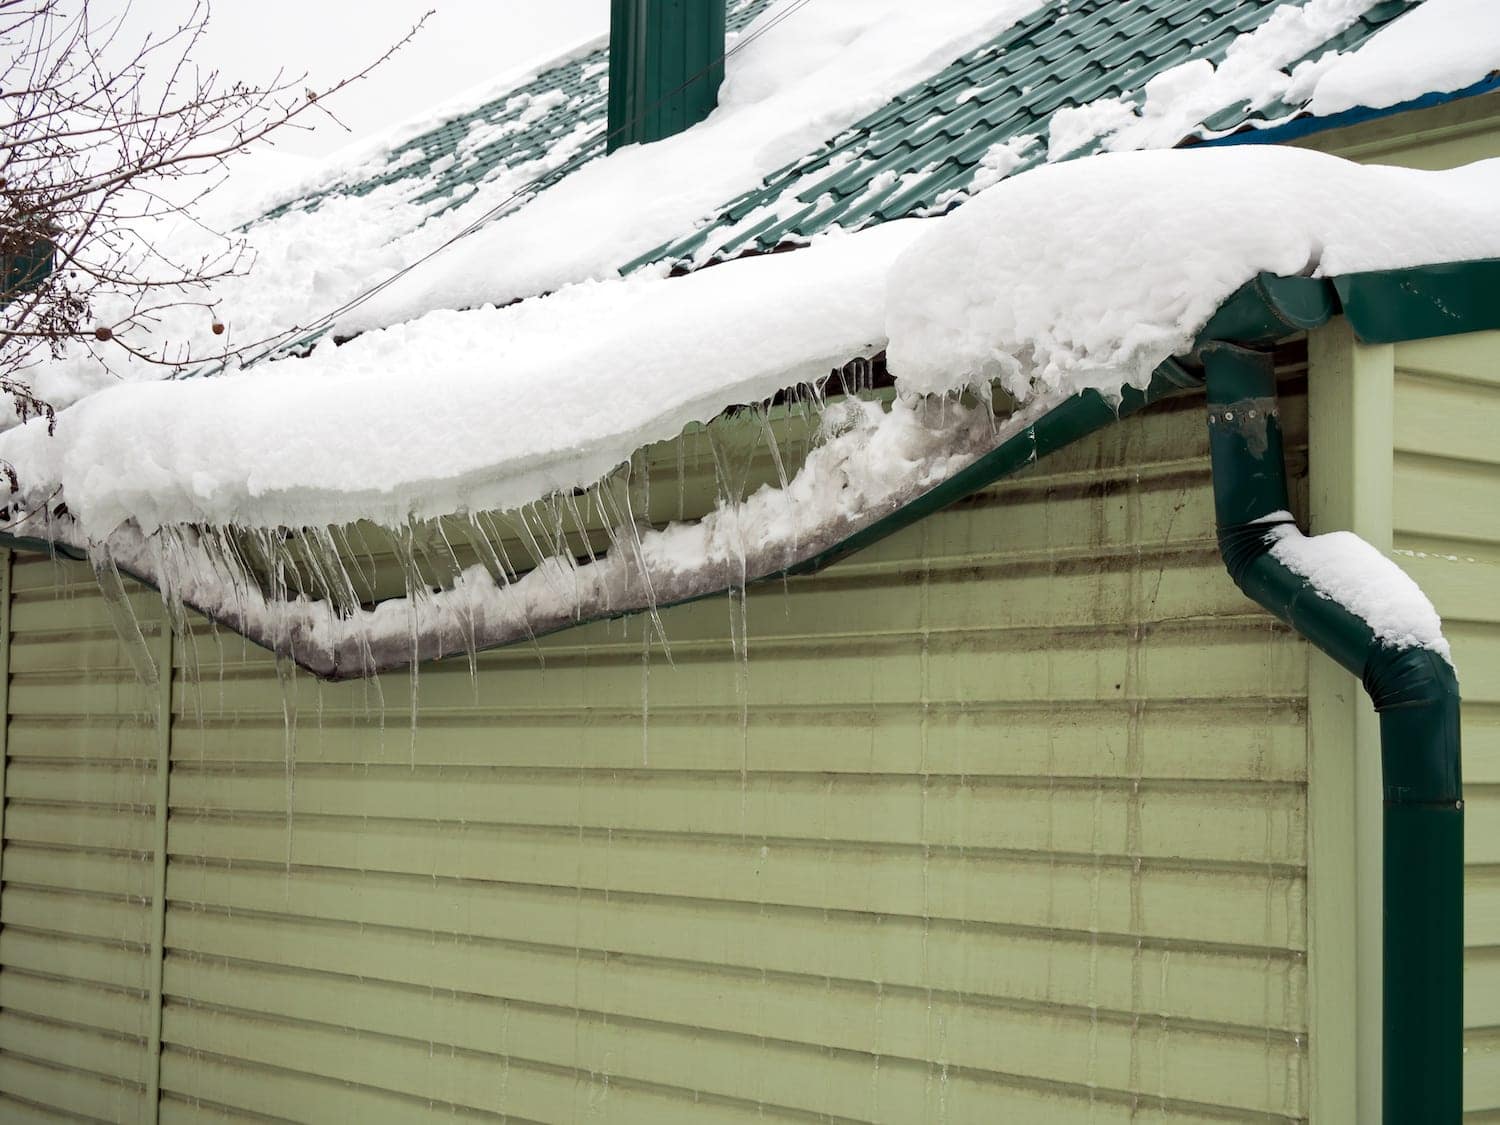
If you are in Traverse City watching icicles grow along the gutter line, what you are really watching is water that no longer has anywhere to drain. As part of our complete Traverse City winter roof services, crews handle ice dam insurance claims across Grand Traverse County.
Why Traverse City Roofs Dam Up: Lake-Effect Load and Freeze-Thaw
Traverse City sits in the lake-effect belt, where a single band can drop a foot on one side of Grand Traverse County and leave the other side clear. That snow lands wet and heavy, packs down on the upper roof, and sits there as a reservoir.
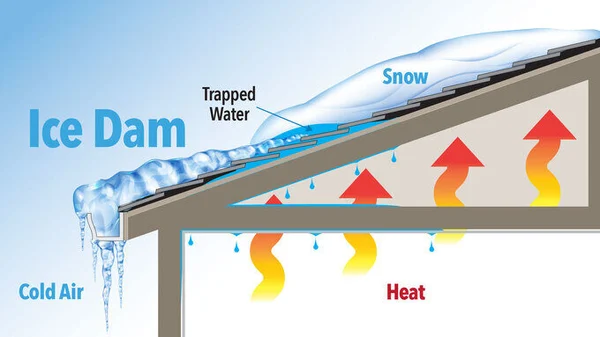
Melting happens from underneath, not from the sun. Attic heat releases water under the pack, it runs to the overhang where there is no heated space below, and it freezes. That is the engine, and in Traverse City it runs most of the winter.
Ice-barrier practice in Grand Traverse County
What matters on a Traverse City roof is not whether ice barrier exists but how far up it runs. Water backed up behind a foot of ice travels much further than the first course, and a membrane that stops short is a membrane that stops working.
Ice Dam Insurance Claims in Traverse City: How The Work Runs
One claim, broken out by coverage
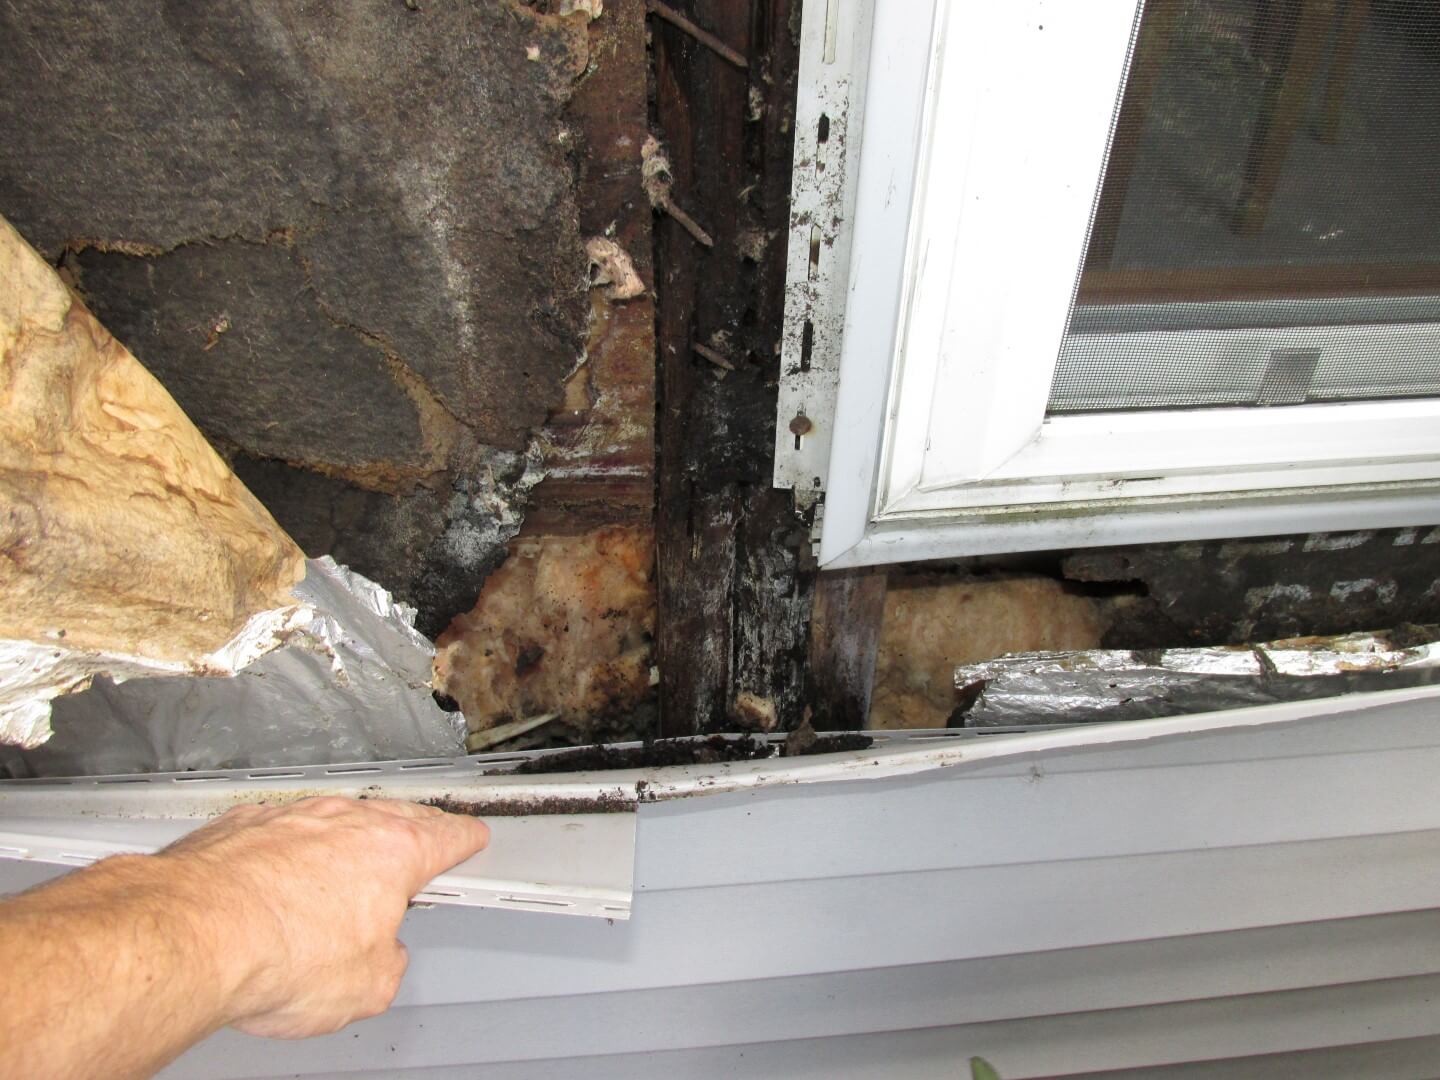
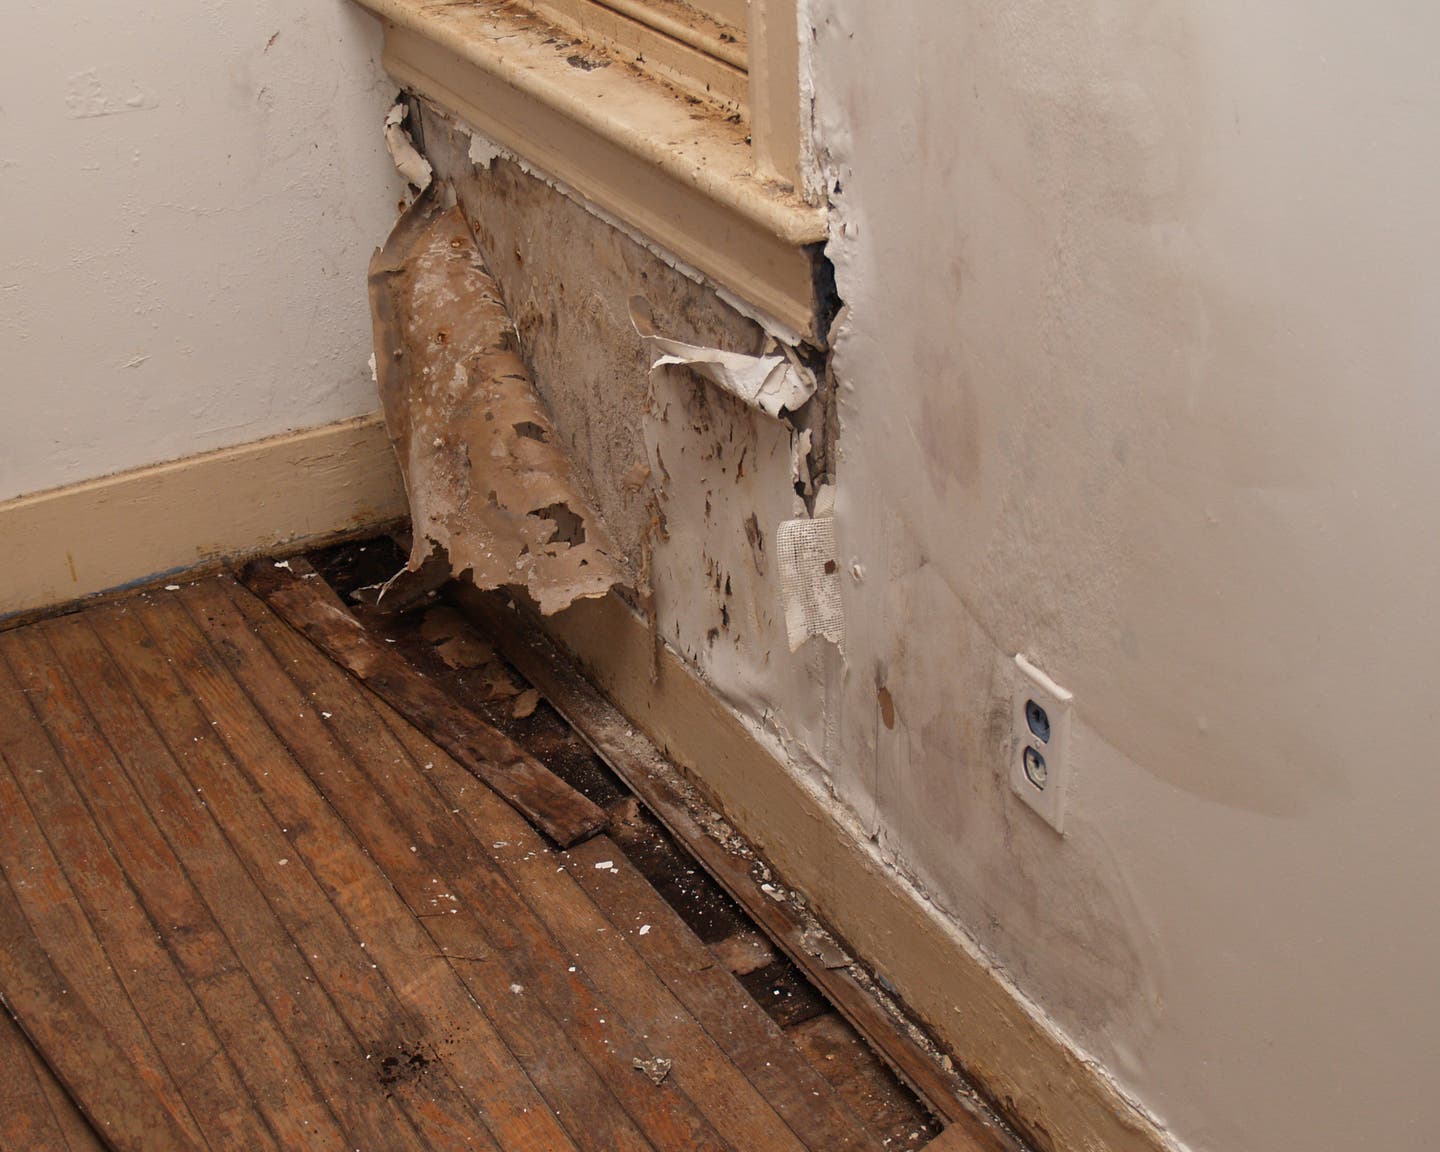
Everything an ice dam caused goes on one claim, but not as one lump number. Emergency removal and dryout are loss mitigation. Mold remediation often sits under its own sublimit. Interior repair and the roof sit under dwelling coverage. Does Insurance Pay for Ice Dam Water Damage?.
Writing the scope with those lines separated is what lets an adjuster approve each part on its own terms, and it stops a dispute over one line holding up the rest of a Traverse City claim.
The limits of what any contractor can do
Ice Dam Now is a restoration contractor, not a public adjuster and not a law firm. Crews document what they find, write defensible scopes and meet adjusters on site. The coverage decision belongs to you and your carrier, and anyone promising to get a specific claim paid is overselling what a contractor can control.
Replacement cost, actual cash value and the second check
Most policies pay the depreciated value first and release the remainder once the repair is actually completed and invoiced. People who do not know that see the first check, assume it is the whole settlement, and decide the claim was not worth filing.
Reading which of those two your policy is on, before the work is scoped, changes what gets claimed and when. The specifics are between you and your carrier - what a contractor supplies is the documentation each stage needs.
Scopes in the format adjusters use
Scopes get written in Xactimate line items, with the mitigation work priced and described the way a carrier's own estimating software describes it. An adjuster comparing like to like approves faster than one translating a hand-written invoice into their system.
Where the policy allows direct billing, carriers are billed directly, so the out-of-pocket conversation is smaller from the start.
When filing is not worth it
Compare the likely scope to the deductible, and weigh how your carrier treats claim history. A single-room stain with no wet insulation often is not worth filing.
Anything involving saturated insulation, multiple rooms or structural drying usually is. You will get a straight read on which before anything is filed.
What you get in Traverse City
- Adjuster meetingsCrews meet the adjuster on site and walk the damage with them
- One claim for the whole eventRemoval, mitigation, mold, interior repair and roof on a single file
- Direct billingCarriers billed directly wherever the policy allows it
| Billing | Xactimate line items on one claim; carrier billed directly where the policy allows |
|---|---|
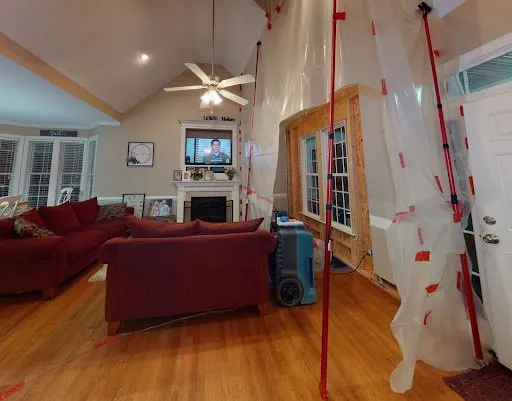
| Method | Containment, HEPA filtration and drying to a measured IICRC standard |
| Interior repair | Insulation, drywall, texture, trim and paint, done in-house after drying |
| Coverage area | Traverse City and Grand Traverse County |
| Local ice-barrier practice | Eave membrane expected on re-roofs |
| Primary climate stressor | Lake-effect bands, wet heavy pack |
| Dispatch window | Same day to 24 hours |
Grand Traverse County Coverage From Traverse City
Crews working Traverse City cover the adjoining communities on the same route — Acme, Grawn, Cedar, Mayfield and Williamsburg — so a storm week usually means one truck handling several addresses in Grand Traverse County rather than separate trips.
Nearest hub towns with their own insurance claims pages: Petoskey, Mount Pleasant, Escanaba, Midland, Alpena, Muskegon.
Traverse City sits inside the regular Michigan service area, so a crew is usually scheduled the same day or the following morning.
Most jobs do not stop at one service. Insurance Claims in Traverse City often runs alongside water mitigation & dryout in Traverse City, and both get written into one scope rather than billed as separate visits.
Active leak right now? Our 24/7 Traverse City steam ice dam removal crews are dispatched first during a freeze event. Call (888) 561-9664.